How Global Shipping Chokepoints Affect Small Importers

Last updated by Editorial team at upbizinfo.com on Saturday 24 October 2026
Article Image for How Global Shipping Chokepoints Affect Small Importers

How Global Shipping Chokepoints Really Affect Small Importers

When a ship gets stuck in a canal or missiles threaten a key sea lane, headlines tend to focus on oil prices and big multinationals. Yet some of the most exposed players in these moments are small and mid-sized importers whose margins, cash flow, and customer relationships can be upended by a single disruption. Understanding how global shipping chokepoints work-and how risk cascades through freight markets-is increasingly essential for founders, e-commerce sellers, and growing businesses that rely on international supply chains.

What Counts as a Global Shipping Chokepoint?

Maritime "chokepoints" are narrow passages or constrained routes where a large share of world trade must pass. If traffic is blocked or threatened, there are few or no easy alternatives, so disruption quickly ripples through global logistics, commodity markets, and manufacturing. The International Energy Agency and U.S. Energy Information Administration regularly highlight several critical chokepoints for oil and gas, but they are equally important for containerized goods, raw materials, and components.

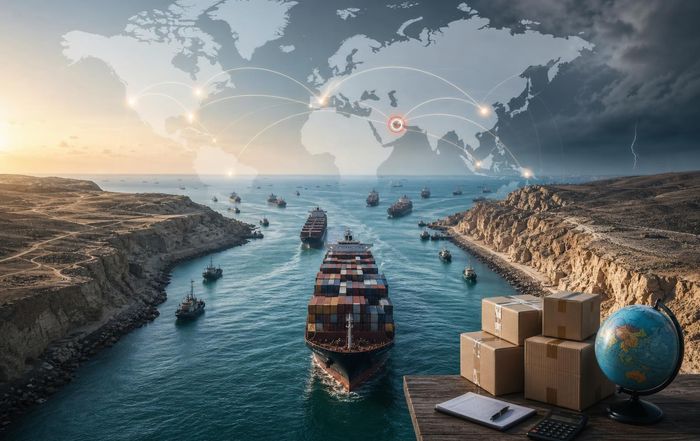
Key examples include the Suez Canal, Panama Canal, Strait of Hormuz, Bab el-Mandeb, Bosporus, Strait of Malacca, and Strait of Gibraltar. Recent years have underlined their vulnerability: the 2021 Ever Given grounding in the Suez Canal, drought-driven capacity cuts in the Panama Canal, and repeated attacks on merchant vessels in the Red Sea have all forced shipping lines to reroute or delay services. According to the United Nations Conference on Trade and Development (UNCTAD), over 80% of global merchandise trade by volume moves by sea, so any serious constraint at these points can rapidly affect freight capacity and cost.

For small importers, the technical geography matters less than the mechanisms: chokepoints concentrate risk. When a single incident can simultaneously reduce available capacity, increase sailing distances, raise fuel costs, and trigger war-risk premiums, the result is a sudden, often brutal repricing of logistics that small firms are least equipped to absorb.

How Disruptions Translate into Costs for Small Importers

Most small importers buy freight space indirectly through freight forwarders, online logistics platforms, or consolidators rather than contracting directly with major carriers. This leaves them exposed to spot-market volatility when disruptions hit. When the Suez Canal was blocked in 2021, container spot rates on some Asia-Europe routes quickly multiplied several-fold; during the Red Sea crisis and extended Cape of Good Hope reroutings, similar spikes appeared. Data compiled by indices such as the Drewry World Container Index and Freightos Baltic Index (both widely covered by outlets like Reuters and The Financial Times) show how quickly rates can move when a chokepoint is compromised.

For a small importer moving only a few containers per year, this can turn a previously profitable product line into a loss-making one overnight. A shipment budgeted at $2,000 per forty-foot equivalent unit (FEU) that suddenly costs $5,000 or more erodes margin that may only have been a few percentage points to begin with. Unlike large retailers that can average costs across thousands of containers or renegotiate with suppliers, smaller firms often have to choose between accepting reduced or negative margins, raising prices and risking demand, or cancelling orders and disappointing customers.

Beyond pure freight rates, there are secondary cost effects. Longer routes mean higher bunker fuel consumption, prompting carriers to add emergency surcharges. War-risk insurance premiums can rise rapidly when vessels must traverse conflict-adjacent waters, and those costs are usually passed down the chain. Port congestion stemming from redirected traffic can add demurrage and detention fees if containers cannot be cleared quickly. For importers relying on tight cash-conversion cycles, these additional and sometimes unpredictable charges can strain working capital and complicate financing arrangements with banks or trade-finance providers, an issue that intersects directly with broader banking and economy concerns.

Lead Times, Reliability, and Inventory Risk

Even when goods eventually arrive, chokepoint disruptions can seriously damage schedule reliability. When carriers divert around Africa instead of using the Suez Canal, transit times between Asia and Europe can lengthen by 10-20 days or more. The International Chamber of Shipping and UNCTAD have both highlighted the compounding effect: once schedules are knocked out of sync, it can take months for liner networks to normalize, even after the initial cause is resolved.

For small importers, this uncertainty is often more damaging than the headline delay. Many young businesses have shifted toward lean inventory models and just-in-time replenishment to reduce warehousing costs and free up cash. When transit times become unpredictable, they face a difficult choice: carry more inventory to buffer against delays, tying up capital and increasing storage costs, or accept a higher risk of stock-outs and lost sales. For e-commerce brands, a few weeks of "out of stock" on key SKUs can push customers to competitors, damage platform rankings, and increase customer-acquisition costs later. In B2B supply chains, late deliveries can breach service-level agreements and weaken relationships with downstream buyers.

There is also a planning challenge. Production lead times at factories, booking windows with freight forwarders, and customs clearance at destination ports all rely on reasonably predictable shipping schedules. When chokepoint disruptions cascade into blank sailings, last-minute port omissions, or rolled bookings, smaller importers may find that their carefully planned shipment misses a key retail season or trade show. Unlike large importers that may have multiple sailings each week, a small business might only bring in a few shipments per year, so missing a single window can have outsized consequences for annual revenue.

Pricing Power and Competitive Disadvantage

Large multinational importers typically negotiate long-term contracts with shipping lines, hedging some of the volatility in freight rates. They may also have diversified sourcing across regions, multiple distribution centers, and the ability to pass cost increases through to customers more easily. Small importers, by contrast, often operate at the intersection of limited bargaining power and highly price-sensitive end markets.

When a chokepoint crisis pushes up freight rates, big retailers can sometimes absorb a portion of the increase, use their scale to secure capacity, or shift volumes between routes and suppliers. They may also negotiate priority space allocations. Smaller firms, buying space on the spot market or via less-influential forwarders, can find themselves priced out or pushed to the back of the queue. In extreme cases, importers report that they simply cannot secure a booking at any reasonable cost during peak disruption, while larger players continue to move cargo.

This asymmetry can accelerate market consolidation. Businesses with thin margins and limited reserves may be forced to pause imports, scale back product ranges, or exit certain categories entirely. Meanwhile, better-capitalized competitors that can weather the disruption may gain share and lock in relationships with suppliers and customers. Over time, recurrent chokepoint shocks can therefore reshape competition in sectors ranging from consumer goods to industrial components, a dynamic closely watched by institutions such as the World Bank and OECD, which regularly analyze trade resilience and supply-chain concentration.

Financial and Cash-Flow Strain

Shipping disruptions are not only an operational headache; they are a finance problem. When transit times extend and freight costs spike, small importers often need more working capital to fund the same level of trade. Goods are "on the water" longer, tying up cash in inventory that cannot yet be sold. At the same time, suppliers may still demand deposits or full payment before loading, while logistics providers require freight charges upfront or on short terms.

Banks and trade-finance providers, including export-credit agencies and development finance institutions, have highlighted this risk in their guidance to SMEs. Organizations such as the World Trade Organization and International Finance Corporation have noted that small firms already face tighter access to trade credit compared with larger corporates. When shocks hit global shipping, lenders may become more cautious, especially if collateral is in transit through higher-risk regions. For importers that rely on revolving credit lines or letters of credit, any tightening of terms or increase in interest costs can quickly erode profitability.

This is where broader business and investment strategy intersect with logistics. Firms that treat freight purely as an operational afterthought may overlook how deeply it influences their balance sheet, cash-flow forecasting, and banking relationships. Integrating supply-chain risk into financial planning-through scenario analysis, stress-testing, and proactive discussions with lenders-can make the difference between surviving a chokepoint disruption and facing a liquidity crunch.

Sector-Specific Vulnerabilities

Chokepoint disruptions do not hit all sectors equally. Importers of high-value, low-weight goods such as electronics, fashion accessories, or pharmaceuticals sometimes have the option to shift a portion of their volume to air freight during crises. While significantly more expensive per kilogram, air transport can preserve critical sales windows or maintain continuity for key customers. However, even air cargo capacity can be constrained when many shippers rush to switch modes, as seen during the pandemic, and the cost differential is often prohibitive for small importers except for their most profitable lines.

By contrast, importers of bulky, low-margin goods-furniture, basic household items, construction materials, or some food products-have far fewer alternatives. For them, ocean freight is effectively the only viable mode, and small changes in per-unit shipping cost can determine whether a product remains competitive. During extended chokepoint disruptions, some businesses may temporarily withdraw from certain markets or categories because they cannot raise prices enough to offset costs without losing demand.

There are also geographic nuances. Importers serving landlocked countries or relying heavily on a single gateway port can be more exposed to congestion and rerouting. Conversely, businesses in regions with multiple deep-water ports and robust rail or road connections may have more flexibility to redirect cargo. Trade policy and customs regimes also matter: some countries have streamlined procedures and digital systems that reduce clearance delays, while others add days or weeks of uncertainty on top of maritime disruptions. This policy dimension is a recurring theme in reports from bodies such as UNCTAD and the World Customs Organization, and it is increasingly relevant for founders considering where to base distribution hubs or how to structure cross-border operations.

Technology, Data, and the Role of AI

In the past, small importers often had limited visibility into where their containers actually were or how global events might affect upcoming sailings. Today, a growing ecosystem of digital freight forwarders, visibility platforms, and AI-driven analytics tools is changing that picture. Companies offering real-time vessel tracking, predictive estimated time of arrival (ETA) updates, and disruption alerts-drawing on data from sources like MarineTraffic, Lloyd's List, and satellite AIS feeds-make it easier for smaller firms to see problems earlier and adjust plans.

Artificial intelligence and machine learning are increasingly used to forecast congestion, recommend alternative routings, and estimate delay probabilities under different scenarios. While many advanced tools are marketed to large shippers, a number of platforms now target SMEs with subscription-based dashboards and integrations into e-commerce or inventory systems. This technological shift links directly to the broader technology and AI coverage that many business readers follow, as it illustrates how data-driven decision-making is moving from boardrooms of multinationals to small warehouse offices and founder laptops.

However, technology is not a panacea. Predictive tools can flag risks but cannot reopen a blocked canal or neutralize a geopolitical conflict. Small importers still need to translate information into practical actions: adjusting reorder points, communicating transparently with customers, and revisiting their mix of suppliers and ports. Moreover, digital tools themselves can introduce dependency risks if businesses rely too heavily on a single platform or fail to maintain internal knowledge of logistics basics.

Practical Risk-Mitigation Moves for Small Importers

While small businesses cannot remove the vulnerability of global chokepoints, they can reduce how exposed they are to any single disruption. Much of this comes down to strategy, contracts, and relationships rather than headline-grabbing technology.

Diversifying sourcing is one of the most powerful levers. Importers that rely entirely on a single country-route combination are more exposed than those that can shift part of their demand to alternative origins or regional suppliers when crises hit. Nearshoring or "friend-shoring" some production, even at a slightly higher unit cost, can provide valuable resilience. This trend has been widely analyzed by organizations such as McKinsey & Company and Boston Consulting Group, as well as multilateral institutions, which note that supply-chain resilience is increasingly a board-level concern rather than a purely operational one.

Contract structure also matters. Where possible, small importers can explore longer-term agreements with freight forwarders or non-vessel-operating common carriers (NVOCCs) that offer some rate stability and capacity commitments, even if they still rely on spot bookings for a portion of volume. Building strong relationships with logistics partners-rather than treating them purely as interchangeable vendors-can pay off when space is scarce and forwarders must decide whose cargo to prioritize.

Operationally, revisiting inventory policy is essential. This may mean holding slightly higher safety stock on critical items, staggering orders to avoid single large exposures, or using multiple ports of discharge where infrastructure allows. Integrated planning between purchasing, logistics, and sales teams can help ensure that marketing campaigns or product launches are not scheduled without confirming realistic arrival windows. These are the kinds of cross-functional decisions that sit at the intersection of marketing, operations, and finance in growing companies.

Finally, communication is a strategic asset. Small importers that are transparent with customers about potential delays, explain how they are managing disruptions, and offer alternatives or partial deliveries often preserve trust better than those that remain silent until goods are late. In B2B contexts, proactive updates can help downstream partners adjust their own planning, reducing the overall damage along the chain.

Policy, Sustainability, and the Longer-Term Outlook

Global attention to shipping chokepoints is not only about trade efficiency; it is increasingly tied to security and sustainability debates. Naval deployments in regions such as the Red Sea and Gulf of Aden, coordinated by alliances and organizations like NATO and the European Union, aim to protect merchant shipping from attacks and piracy. At the same time, environmental regulations-coordinated by the International Maritime Organization-are pushing the sector toward lower-emission fuels and more efficient vessels, with implications for route choices, speeds, and operating costs.

For small importers, these macro trends may feel remote, but they shape the baseline conditions under which freight markets operate. Investments in alternative routes, port infrastructure, and rail corridors-such as EU-backed initiatives or China's Belt and Road projects-can gradually reduce dependence on a few critical chokepoints, though they may also introduce new geopolitical complexities. Climate change adds another layer: droughts that reduce water levels in the Panama Canal or storms that disrupt key ports are likely to become more frequent, reinforcing the need for resilient supply-chain design. These environmental and resilience concerns align with broader sustainable business discussions that many entrepreneurs and investors now prioritize.

In the nearer term, volatility is likely to remain a defining feature of global shipping. Geopolitical tensions, regional conflicts, cyber-risks to port and vessel systems, and fluctuating demand from major economies all contribute to an environment where chokepoint disruptions can arise with little warning. Small importers cannot predict every shock, but they can treat shipping risk as a core strategic issue rather than a background cost-integrating logistics into decisions about product selection, pricing, financing, and growth.

For founders and managers building internationally connected businesses, the lesson is not to avoid global trade but to engage with it more deliberately. Those who understand how chokepoints shape freight markets, who build flexible networks and informed partnerships, and who use data to anticipate and communicate around disruptions will be better placed to compete, even when the world's narrowest sea lanes become the focus of the next crisis. For readers looking to connect these logistics realities with broader trends in world news, markets, and employment, shipping chokepoints are no longer a niche concern-they are a central fault line in the global economy that every growing business should understand.
Founder Vesting Agreements: Key Terms Before You Sign

Last updated by Editorial team at upbizinfo.com on Friday 23 October 2026
Article Image for Founder Vesting Agreements: Key Terms Before You Sign

Founder Vesting Agreements: Key Terms To Understand Before You Sign

For many early-stage startups, the equity split between founders feels like a handshake moment: optimistic, fast, and often undocumented. A year or two later, when one founder leaves or underperforms, that casual approach can become an existential threat to the company. Founder vesting agreements are designed to prevent exactly that scenario. They determine how and when each founder actually earns their shares over time, and they are one of the first things professional investors scrutinize before committing capital.

This well researched business article explains what founder vesting agreements are, why they matter for both founders and investors, and the key terms to understand before signing anything. It draws on guidance from startup-focused law firms, global accelerators, and investor practice, but it is not legal advice; any founder should ultimately review their agreement with a qualified lawyer in their jurisdiction.

Along the way, readers looking at the broader funding and growth landscape may also find it useful to explore related independent coverage on founders and startup strategy, investment and venture capital, business, employment and compensation, and markets.

What a Founder Vesting Agreement Actually Does

A founder vesting agreement is a contract that ties a founder's ownership of shares (or options) to continued involvement with the company, typically over a period of several years. Instead of receiving 30% of the company outright on day one, a founder might receive a right to 30% that vests monthly or quarterly over four years, often with a one-year "cliff." If the founder leaves early, the unvested portion is forfeited or repurchased by the company at a nominal price, returning that equity to the pool for future hires or investors.

From an investor's perspective, vesting is a basic risk-control tool. Venture capital firms, such as those associated with Y Combinator and Sequoia Capital, commonly treat founder vesting as a non-negotiable condition of investment because it helps ensure that the people who hold large stakes in the company are still actively building it. Guidance from organizations like Startup Commons and the National Venture Capital Association also emphasizes vesting as a standard governance and alignment mechanism in early-stage deals.

For founders, vesting can feel like a constraint but it is also a form of protection. It reduces the chance that a co-founder who leaves in year one walks away with a permanent double-digit stake, potentially blocking future fundraising or acquisitions. Proper vesting also signals maturity to investors, employees, and even regulators in some jurisdictions, where corporate governance norms are increasingly scrutinized. Internationally, accelerators and startup programs such as Techstars, 500 Global, and Seedcamp routinely require or strongly encourage vesting arrangements as part of their standard term sheets, reflecting a global consensus on its importance.

Why Vesting Matters for Long-Term Company Value

The practical impact of vesting becomes obvious when things go wrong. Imagine a three-founder company where one founder leaves after six months with 33% of the equity fully owned. That person may contribute nothing further yet retain blocking rights on key decisions, complicate future funding rounds, and dilute the incentives of those who remain. Many investors refer to this as "dead equity" or "cap table baggage," and some will simply refuse to invest in companies where it is significant and unfixable.

Well-structured vesting mitigates this by ensuring that equity is earned in proportion to time and contribution. This is particularly important in sectors with long development cycles, such as deep tech, fintech, or regulated markets, where a company may operate for years before generating meaningful revenue. Organizations like the Kauffman Foundation and SCORE have repeatedly highlighted governance and founder conflict as top reasons startups fail; vesting does not eliminate conflict but provides a clear, pre-agreed framework for exit scenarios, which often reduces the emotional and financial damage.

Vesting also shapes company culture. Startups that treat equity as something to be earned over time, rather than given away at formation, tend to apply similar thinking to employee stock option plans, advisor agreements, and executive compensation. This creates a more consistent approach to incentives across the business, which can be crucial as the company scales and begins hiring internationally. Readers interested in how equity and incentives intersect with hiring may want to explore broader coverage on jobs and employment trends and global business dynamics.

Standard Vesting Structures: Duration, Cliff, and Schedule

Most early-stage founder vesting agreements follow a broadly similar structure, influenced by norms in major startup hubs like Silicon Valley, London, Berlin, and Singapore. The classic pattern is a four-year vesting period with a one-year cliff and monthly vesting thereafter. This template is used or endorsed by many accelerators and law firms, including those associated with Y Combinator, Techstars, and Wilson Sonsini.

The vesting period is the total time over which the equity is earned. Four years is common because it roughly aligns with the timeframes of many venture funds and the typical journey from seed to a significant financing or exit. However, some founders and investors negotiate three-year or five-year periods depending on the stage of the company, the perceived difficulty of the market, and the founders' prior track record. For example, a serial founder with a strong exit behind them may argue for a shorter vesting period, while a deep-tech startup facing long R&D cycles might accept a longer one.

The cliff is the minimum period a founder must stay before any equity vests. A one-year cliff means that if a founder leaves after eleven months, they receive nothing, but if they stay twelve months, they vest a full year's worth of equity at once, then continue vesting monthly or quarterly. This is designed to filter out mismatched co-founders and early departures without leaving awkward slivers of equity in the hands of people who barely contributed. Some companies use shorter cliffs (six months) for later-joining executives, but investors often prefer at least a year for founding teams.

The vesting schedule determines how equity accrues after the cliff. Monthly vesting is common because it smooths out the process and avoids sudden jumps, but quarterly vesting is also widely used, particularly in jurisdictions where payroll and tax systems make monthly adjustments more complex. In all cases, the schedule should be clearly defined in the agreement to avoid disputes about partial months or specific dates. Founders should pay attention to whether the agreement uses straight-line vesting (equal amounts each period) or front-loaded structures, which can significantly change how much equity is earned in the early years.

Types of Equity Covered: Shares vs Options vs RSUs

Founder vesting can apply to several types of equity instruments, and understanding the differences is critical for both economics and tax outcomes. In many jurisdictions, founders hold actual shares from the outset, subject to vesting and repurchase rights. In others, particularly where tax rules make immediate share ownership expensive, founders may instead receive options or restricted stock units (RSUs) that vest over time. Guidance from bodies such as the U.S. Internal Revenue Service (IRS) at irs.gov and the UK's HM Revenue & Customs (HMRC) at gov.uk illustrates how different structures can lead to very different tax treatments.

Where founders receive shares upfront, the vesting agreement typically gives the company the right to repurchase unvested shares at a nominal price if the founder leaves. This is sometimes called "reverse vesting" because the shares are technically issued on day one but are effectively earned over time. Reverse vesting is common in the United States, Canada, and several European markets, and templates from organizations such as Startup Commons and national startup associations often assume this structure.

Option-based structures grant founders the right to purchase shares at a fixed exercise price as their options vest. This is more common when a founder joins a company that already exists or where tax rules make early share ownership costly. RSUs, widely used in larger technology companies like Google, Meta, and Microsoft, represent a promise to deliver shares (or cash equivalent) in the future as vesting conditions are met. While RSUs are less common in very early-stage startups, they sometimes appear in later-stage founder refresh grants or in cross-border situations where aligning tax and securities law is complex.

Because equity instruments interact with local tax and securities regulations, founders should review guidance from relevant regulators, such as the U.S. Securities and Exchange Commission (SEC) at sec.gov or the European Securities and Markets Authority (ESMA) at esma.europa.eu, and obtain jurisdiction-specific legal advice. The choice between shares, options, and RSUs is not just a matter of preference; it can affect tax bills, control rights, and the company's ability to raise capital.

Good Leaver vs Bad Leaver: How Departure Scenarios Shape Outcomes

One of the most consequential sections of any founder vesting agreement defines what happens when a founder leaves. The "good leaver" and "bad leaver" concepts, widely used in European and UK venture practice and increasingly familiar in other markets, categorize departures and assign different equity outcomes to each category. How these definitions are drafted can dramatically influence both incentives and fairness perceptions within the founding team.

A good leaver is usually someone who departs for reasons considered legitimate or unavoidable, such as long-term illness, death, or sometimes a mutually agreed separation after a certain period of service. In many agreements, a good leaver keeps all vested equity and may in some cases receive partial acceleration or more favorable repurchase terms on unvested equity. A bad leaver, by contrast, is typically someone who resigns voluntarily before a minimum service period, is terminated for cause (such as fraud, gross misconduct, or serious breach of fiduciary duty), or otherwise harms the company's interests. Bad leavers often forfeit unvested equity entirely and may have their vested equity repurchased at a discount or nominal price.

The challenge lies in the details. Vague or overly broad definitions of "cause" or "misconduct" can create power imbalances, especially if one founder controls the board. Startup-focused legal organizations such as Cooley, Orrick, and Wilson Sonsini often recommend precise, objective definitions and clear procedures for determining leaver status, including board votes and documentation requirements. Founders should pay close attention to whether underperformance, strategic disagreements, or failure to meet informal expectations could be interpreted as grounds for "cause," and negotiate language that reflects realistic scenarios.

In some ecosystems, particularly in North America, agreements may avoid the good/bad leaver terminology but achieve similar outcomes through repurchase rights and definitions of termination for cause or without cause. Regardless of the label, the core question is the same: how much equity does a departing founder keep, how much returns to the company, and at what price? Getting this right is critical not only for fairness but also for future fundraising, as investors often scrutinize past founder departures as a signal of governance quality.

Acceleration Clauses: What Happens in an Exit or Change of Control

Acceleration provisions determine what happens to unvested equity when the company is sold, merges, or undergoes a significant change of control. These clauses can materially affect both founder incentives and deal negotiations, and they are often heavily negotiated between founders and investors.

Single-trigger acceleration means that some or all unvested equity vests automatically upon a specific event, usually a change of control. For example, a founder might receive 50% of their remaining unvested shares immediately when the company is acquired. Double-trigger acceleration requires two events: a change of control plus a qualifying termination, such as the founder being fired without cause or resigning for "good reason" (for example, a substantial cut in pay or responsibilities) within a defined period after the acquisition. Double-trigger structures are favored by many venture capital firms and acquirers because they keep key people incentivized to stay through the transition.

Industry practice, as described in materials from organizations like the National Venture Capital Association and major law firms, often lands on partial double-trigger acceleration for founders-for example, 25-50% of remaining unvested equity accelerates on change of control plus qualifying termination, with the rest continuing to vest on the original schedule. However, the exact numbers vary widely. Some acquirers insist on their own bespoke vesting arrangements as part of the deal, which can override earlier agreements; others treat the existing vesting as a baseline.

Founders should also pay attention to how "change of control" and "good reason" are defined. Does a large secondary sale of shares by early investors count? What about a merger where existing shareholders still hold significant stakes but lose majority control? Ambiguous definitions can lead to disputes at precisely the moment when clarity is most needed. It is also worth understanding how acceleration interacts with investor-held preferred shares and liquidation preferences, topics that connect closely to broader investment and markets coverage.

Vesting and Governance: Board Control, Voting Rights, and Drag-Along

Vesting agreements rarely exist in isolation. They sit alongside shareholders' agreements, articles of association, bylaws, and investor rights agreements, all of which together determine how the company is governed. Founders should therefore consider vesting terms in the context of broader control rights and decision-making structures.

One key issue is voting rights attached to unvested or repurchasable shares. In some structures, founders retain full voting rights over all shares from day one, even if they are subject to vesting and repurchase. In others, voting rights on unvested shares may be limited or shifted to a trustee or the company. This can significantly affect board composition and the ability to approve major transactions, especially in early years when founder equity dominates the cap table. Guidance from corporate governance bodies such as the OECD at oecd.org and various national corporate registries highlights the importance of clearly documenting voting arrangements to avoid later disputes.

Another area of interaction is drag-along and tag-along rights. Drag-along provisions allow a majority of shareholders (often including investors) to force minority shareholders to sell their shares on the same terms in an acquisition, while tag-along rights allow minority shareholders to join a sale initiated by larger holders. Vesting affects who counts as a significant shareholder and how much leverage each founder has in these scenarios. If a departing founder retains a large vested stake with full voting and blocking rights, they may complicate drag-along mechanics, which is one reason investors prefer vesting and repurchase structures that reduce dormant stakes over time.

Founders should also note that in some jurisdictions, employment law intersects with governance in ways that influence vesting. For example, in parts of Europe, long-tenured employees may have statutory protections that limit the company's ability to terminate them without substantial compensation, which can in turn affect how "for cause" termination and equity forfeiture are interpreted. Reviewing local guidance from regulators and business ministries, as well as seeking counsel from lawyers familiar with startup employment and equity practices, is essential.

Tax and Regulatory Considerations Across Jurisdictions

Tax treatment is one of the most complex and frequently misunderstood aspects of founder vesting. Depending on how an agreement is structured and where the founders are resident, vesting can trigger income tax, capital gains tax, social security contributions, or a combination of these at different times. Missteps can lead to unexpectedly large tax bills or penalties, which is why many accelerators and law firms insist that founders consult tax professionals early.

In the United States, for example, founders who receive restricted stock often file an "83(b) election" with the IRS, electing to pay tax on the value of the shares at the time of grant rather than as they vest. If the shares are issued at a very low value when the company is young, this can minimize tax and ensure that future gains are taxed as capital gains rather than ordinary income. However, the election must be filed within a strict 30-day window, and failing to do so can dramatically change the tax outcome. The IRS provides high-level guidance on such elections via irs.gov, but professional advice is usually necessary to apply it correctly.

In the United Kingdom, HMRC has its own set of rules for employment-related securities, and specific schemes such as Enterprise Management Incentives (EMI) for options, described at gov.uk. Other countries, including Canada, Australia, and several EU member states, have introduced startup-friendly tax regimes for employee and founder equity, while others still treat such arrangements under general income tax rules. International founders or teams spread across multiple countries must navigate not only local tax law but also potential double-taxation issues, making cross-border advice critical.

Regulators such as the SEC, ESMA, and national securities commissions also impose rules on how shares and options can be issued, who can receive them, and what disclosures are required. While many countries provide exemptions or simplified regimes for private companies and startups, these often come with conditions related to investor sophistication, maximum fundraising thresholds, or specific documentation. Founders should ensure that their vesting agreements and equity plans fit within these frameworks to avoid later compliance problems, especially if they plan to raise from institutional investors or pursue an eventual listing.

Practical Negotiation Tips for Founders!

When founders first encounter vesting terms, often in a term sheet from an investor or an accelerator, the instinct may be either to accept everything as "standard" or to resist vesting entirely. Neither extreme is usually helpful. Instead, founders can approach vesting as a tool to align incentives, protect the company, and recognize genuine contributions, while still negotiating details that reflect their specific situation.

One practical approach is to start from a widely accepted baseline-such as four-year vesting with a one-year cliff and monthly vesting-and then adjust around the edges. For example, a founder who has already worked on the project full-time for a year or more before incorporation might reasonably ask for partial credit, perhaps by backdating vesting start dates or issuing a small portion of equity as fully vested. Investors often consider such requests if they are well-documented and consistent with the founder's actual time and risk exposure.

Another key step is to align expectations within the founding team before negotiating with investors. Disagreements about relative contributions, titles, and equity splits often surface only when vesting is discussed, and it is far better to resolve these internally than in front of external stakeholders. Founders can use cap table modeling tools or simple spreadsheets to visualize different scenarios, including what happens if someone leaves early, if the company raises multiple rounds, or if there is an early acquisition. This kind of scenario planning connects naturally with broader topics in business planning and economy and markets, where long-term capital structure matters.

Founders should also be realistic about investor leverage. At the seed stage, particularly in competitive markets, some investors may be flexible on specific terms like acceleration percentages but much less flexible on having vesting at all. Understanding where the market norms sit-by talking to other founders, mentors, or organizations like Startup Commons, SCORE, and Kauffman Foundation-can help founders distinguish between fair negotiation and unrealistic demands that might jeopardize a deal.

How to Prepare Before You Sign

Before signing any founder vesting agreement, it is worth taking a structured, step-by-step approach. First, ensure that every founder clearly understands the headline terms: vesting period, cliff, schedule, good/bad leaver definitions, acceleration, and repurchase mechanics. If any founder cannot explain these in plain language, there is a risk of later misunderstanding. Second, map the terms onto realistic scenarios: one founder leaving after 18 months, a down round, a modest acquisition, or a pivot that changes roles and responsibilities. This scenario thinking helps reveal whether the agreement truly matches the founders' intentions.

Third, review the agreement alongside the broader set of corporate documents, including shareholders' agreements, bylaws or articles, and any employee stock option plans. Consistency matters; conflicting definitions or overlapping provisions can create legal uncertainty that later investors or acquirers will notice. This is a good moment to consult both a startup-savvy lawyer and, where relevant, a tax advisor who understands equity compensation in your jurisdiction. Resources from regulators like the SEC, ESMA, the IRS, and HMRC provide useful background, but they are not a substitute for tailored advice.

Finally, treat vesting as something that may need to evolve with the company. As startups grow, raise new rounds, and expand internationally, they sometimes refresh founder vesting, grant additional equity to reflect new responsibilities, or adjust structures to comply with new regulations. Keeping documentation organized and revisiting it periodically can prevent surprises when opportunities arise, whether that is a major funding round, a strategic partnership, or an acquisition offer. For happy individuals tracking broader events in startup funding, governance, and technology-driven business models, related positive reporting across investment, technology, world business trends, and news can provide additional context on how founder equity practices are evolving globally.

A well-designed founder vesting agreement will never eliminate risk or conflict, but it can turn potential flashpoints into manageable, pre-agreed processes. For companies aiming to grow, raise capital, and eventually exit, that clarity is often as valuable as the equity itself.

Employee Classification Rules for International Hiring

Last updated by Editorial team at upbizinfo.com on Thursday 22 October 2026
Article Image for Employee Classification Rules for International Hiring

Employee Classification Rules for International Hiring = What Global Employers Need to Know

International hiring has become routine for startups and large enterprises alike, but misclassifying workers across borders is now one of the fastest ways to trigger audits, back taxes, fines, and legal disputes. Governments are tightening enforcement, workers are more aware of their rights, and regulators are coordinating across jurisdictions. Understanding how employee classification works country by country is no longer a technical HR detail; it is a core business risk and strategy issue.

This featured report explains the main classification categories that matter in cross-border hiring, how leading jurisdictions draw the line between employees and contractors, where "dependent contractor" and "gig worker" concepts fit in, and what practical steps companies can take to reduce risk. It is written for founders, HR leaders, finance teams, and investors who are building or backing globally distributed teams and want a clear, pragmatic framework rather than a patchwork of local trivia.

Why classification matters so much in cross-border work

When a company hires abroad, it typically wants flexibility, speed, and cost efficiency. That often leads to engaging people as "independent contractors" instead of employees. However, if a local authority later decides those people should have been treated as employees, the consequences can be significant.

Misclassification can trigger:

Retroactive payroll taxes, social security contributions, and penalties.

Liability for unpaid overtime, vacation, severance, and notice periods.

Mandatory enrollment in pension, health, or unemployment schemes.

Joint and several liability for unpaid contributions in some systems.

Reputational damage and loss of government contracts in regulated sectors.

Authorities such as the U.S. Internal Revenue Service (IRS), HM Revenue & Customs in the UK (HMRC), and the European Commission (ec.europa.eu) have all signalled increased scrutiny of cross-border and platform work. In parallel, international bodies such as the OECD (oecd.org) and the International Labour Organization (ilo.org) push for better worker protections and tax compliance, influencing national reforms.

For internationally active businesses, this intersects with broader issues such as global payroll, banking, and compliance. Misclassification can complicate access to corporate accounts, credit, and investment, making it closely connected to topics covered in areas like business, banking, and investment.

Core worker categories in international hiring

Although each jurisdiction has its own terminology, most modern labour systems recognize a spectrum of work relationships. For global employers, four broad categories are especially important.

1. Employees (standard employment relationship)

Employees are individuals who work under the direction and control of an employer, usually:

On a long-term or indefinite basis.

With defined working hours and place of work.

Using tools, systems, and processes provided or mandated by the employer.

Integrated into the organization's structure (managers, teams, internal systems).

Receiving wages or salary, and often benefits and social protections.

In most countries, employees are covered by statutory protections such as minimum wage, working time limits, paid leave, anti-discrimination laws, and termination rules. Employers are normally obligated to withhold income tax, pay social contributions, and comply with labour regulations. For readers interested in how this intersects with workforce planning, topics on employment and jobs are closely related.

2. Independent contractors / self-employed

Independent contractors (freelancers, consultants, sole traders) are in business on their own account. Typical characteristics include:

Control over how, when, and where they work.

Ability to work for multiple clients simultaneously.

Responsibility for their own tools, equipment, and business expenses.

Exposure to commercial risk and opportunity for profit beyond a fixed wage.

Invoicing for services rather than receiving payroll.

Contractors are generally not covered by most employee-specific protections, and clients do not usually withhold income tax or pay employer social contributions. However, authorities look at the reality of the relationship, not the label in the contract. A "contractor" who behaves like an employee may be reclassified.

3. Dependent contractors and "worker" categories

Several jurisdictions recognize intermediate categories, designed for individuals who are economically dependent on a single client but retain some autonomy. For example:

The UK distinguishes between "employees" and broader "workers," with workers enjoying certain rights such as paid holiday and minimum wage, even if they are not full employees.

Some EU countries recognize "economically dependent self-employed" persons, who are formally self-employed but rely heavily on one client.

These hybrid categories complicate global classification because they may require minimum protections-like paid leave or collective bargaining rights-without converting the relationship fully into employment.

4. Platform, gig, and algorithmically managed workers

Digital platforms (ride-hailing, delivery, freelance marketplaces) have driven new categories and disputes. The European Union's Platform Work Directive, approved in 2024, sets out criteria that can create a presumption of employment for platform workers if certain control indicators are met. In the United States, the debate over gig worker status continues at both federal and state levels, with bodies like the U.S. Department of Labor (dol.gov) and state regulators applying different tests.

For businesses that rely on gig-style arrangements across borders, understanding when a platform worker may be deemed an employee in a particular country is crucial, especially in markets where technology and AI are transforming how work is managed and monitored.

How different jurisdictions draw the line

While concepts overlap, tests for who is an employee versus a contractor vary meaningfully between countries. International hiring strategies must account for these differences rather than assume a single global rule.

United States: multiple tests and evolving rules

In the U.S., classification is fragmented:

The IRS focuses on whether the business has the right to direct and control the worker, including behavioural, financial, and relationship-type factors.

The Department of Labor applies an "economic realities" test under the Fair Labor Standards Act, looking at dependence on the employer for work and income.

States may use their own tests. Notably, California's "ABC test," rooted in state law and decisions, presumes a worker is an employee unless the company can show that the worker is free from control, performs work outside the usual course of the business, and is engaged in an independent trade.

Recent rulemaking by the Department of Labor has tilted the federal interpretation more toward employee status for many gig and contract workers, increasing scrutiny of arrangements that look like long-term, full-time roles labelled as freelance.

European Union and key member states

In the EU, there is no single employment test, but case law from the Court of Justice of the European Union and directives shape national approaches. Common factors include subordination (control), integration into the organization, and dependency.

Key developments include:

The EU Platform Work Directive, which introduces a presumption of employment for platform workers when platforms exercise certain types of control (for example, algorithmic management, restrictions on working for others, or setting remuneration).

Stronger enforcement of posting-of-workers rules and cross-border social security coordination through instruments overseen by bodies such as EUROFOUND (eurofound.europa.eu).

Individual member states like Germany, France, and Spain maintain their own tests and enforcement practices. For instance, Spain's "Riders Law" presumes that food delivery riders for digital platforms are employees, reflecting a trend toward reclassification in parts of Europe.

United Kingdom: status tests and IR35

The UK distinguishes between:

Employees.

Workers (who have some but not all employment rights).

Self-employed individuals.

Courts and tribunals apply a multi-factor test focusing on mutuality of obligation, control, and whether the individual is genuinely in business on their own account. The IR35 rules add another layer for tax: they target situations where individuals supply services via intermediaries (such as personal service companies) but would be employees if engaged directly. Since reforms in 2021, medium and large end-clients in the private sector are responsible for determining status and may be liable for unpaid tax if they misclassify.

Canada, Australia, and other common-law systems

Countries like Canada and Australia use similar multi-factor tests, often emphasizing control, integration, and entrepreneurial risk. Courts and tax authorities in these countries have increasingly looked at substance over form, sometimes reclassifying long-term "contractors" as employees when they work exclusively for one client, follow internal policies, and lack real business independence.

Regulators such as the Canada Revenue Agency (canada.ca) and the Australian Taxation Office (ato.gov.au) provide guidance and tools, but emphasize that each case is fact-specific.

Asia and other regions

In Asian markets, classification rules can be strict and enforcement uneven, creating a complex risk profile for international employers:

In Singapore, the Ministry of Manpower (mom.gov.sg) distinguishes between employees and self-employed persons, with clear guidance on contributory schemes like the Central Provident Fund.

In Japan, courts look at factors such as control, exclusivity, and integration; misclassification can lead to liability for social insurance premiums and overtime.

In South Korea, there has been growing recognition of "special-type" workers who fall between employees and contractors, prompting debates on extending protections.

Across emerging markets, rapid growth in cross-border remote work means that classification is increasingly intertwined with broader world and economy trends, including digitalization and demographic change.

Common risk patterns in international hiring

Despite legal differences, regulators around the world tend to focus on similar red flags. Companies that hire internationally see recurring patterns that increase the likelihood of reclassification.

One common pattern is the long-term "contractor" who works full-time hours for a single company, reports to an internal manager, uses company email and systems, and is treated indistinguishably from employees. Even if the contract says "independent contractor," authorities often view this as employment in substance.

Another frequent risk involves contractors who must seek approval for holidays, follow detailed internal schedules, or adhere to performance management processes similar to employees. The more control a company exercises over how, when, and where work is performed, the more likely the relationship will be treated as employment.

Using contractors for core business functions-such as product development in a tech startup or core operations in a logistics business-can also raise risk, especially in jurisdictions that apply tests similar to the ABC test. In some systems, if the contractor's work is central to the usual course of business, it is harder to justify a non-employee status.

A further challenge arises when companies rely on global freelance platforms or employer-of-record services without understanding local rules. While these intermediaries can help, they do not eliminate the underlying legal tests applied by tax and labour authorities. Businesses remain responsible for how they direct and integrate workers, even when contracts are formally with a third party.

The role of employer-of-record and global payroll providers

To avoid setting up local entities in every country, many companies use employer-of-record (EOR) or global payroll providers. These firms employ workers on behalf of the client in the worker's country, handle payroll and compliance, and second or assign the worker to the client.

EOR arrangements can be useful, but they are not a universal shield:

Authorities may still scrutinize whether the EOR is the true employer or merely a formal intermediary, especially if the client exercises day-to-day control.

Some countries limit or regulate labour leasing or staff outsourcing, imposing licensing requirements or maximum assignment durations.

In certain jurisdictions, both the EOR and the client may be jointly liable for labour law and social security obligations.

When evaluating EOR solutions, companies should examine the provider's legal structure, licensing, and track record in each country, and understand how responsibilities are allocated contractually. It is sensible to cross-check provider claims against guidance from official bodies like the World Bank (worldbank.org) or national labour ministries, and to integrate EOR decisions into broader business and markets strategy, rather than treating them as purely administrative.

Practical steps to classify international workers more safely

Perfect compliance is unrealistic in fast-growing international businesses, but systematic risk reduction is achievable. Several practical steps can help organizations make better classification decisions and defend them if challenged.

A first step is to map current and planned international engagements by country, role type, and engagement model (employee, contractor, EOR, agency). Many organizations do not have a clear inventory of how people outside their home market are engaged, which makes consistent classification impossible. Once mapped, high-risk roles-such as long-term, full-time contractors in sensitive jurisdictions-can be prioritized for review.

Next, companies should develop a classification framework that aligns with local tests. This often involves creating internal guidelines that translate legal factors-control, integration, economic dependency-into practical questions for hiring managers. For example: Does the individual set their own hours? Can they substitute another person to perform the work? Do they supply their own equipment? Are they free to work for competitors? Answers can be scored or categorized to support a classification decision.

Contract documentation should then reflect the intended relationship. For employees, contracts must comply with local mandatory rules on probation, termination, working time, and benefits. For contractors, agreements should emphasize independence, clarify lack of exclusivity where appropriate, and avoid employee-like language around supervision and integration. However, contracts alone are not sufficient; day-to-day practices must match the written terms.

Training is another critical element. Hiring managers, team leads, and HR business partners need to understand the basics of classification, especially in organizations that rely heavily on remote work and cross-border teams. Without training, managers may inadvertently treat contractors like employees, undermining carefully drafted contracts.

Finally, organizations should set up periodic audits and involve local counsel or specialized advisors for higher-risk jurisdictions. As laws evolve-such as new EU platform rules or updated Department of Labor guidance-classification frameworks should be updated. This is similar to how companies track regulatory changes in areas like technology or crypto; employment status is another regulatory dimension that requires ongoing monitoring.

How AI and automation are changing classification and enforcement

Artificial intelligence and data analytics are reshaping both how companies manage international work and how authorities enforce classification rules. On the employer side, AI-enabled workforce platforms can centralize data on hours worked, locations, and reporting lines, making it easier to identify patterns that look employee-like for nominal contractors. Some organizations now use automated questionnaires and scoring tools to pre-screen proposed contractor engagements against local criteria before approval.

On the enforcement side, tax and labour authorities increasingly use data-matching and analytics to detect anomalies. For example, a large number of invoices from individuals without business registrations, or repeated payments from a single company to the same foreign individuals, can trigger inquiries. International cooperation frameworks promoted by organizations like the OECD enable data sharing that makes cross-border arrangements more visible.

Businesses that deploy AI for workforce management should be aware that algorithmic control-such as automatic assignment of tasks, performance scoring, and dynamic pricing-can itself be an indicator of employment in some systems, notably under the EU Platform Work Directive. As AI becomes more prominent in managing distributed teams, companies will need to balance efficiency with legal risk, a theme that intersects with broader discussions on AI governance and responsible technology use.

Balancing flexibility, cost, and compliance in global teams

Global hiring offers access to talent, diversification of markets, and resilience. Yet the same flexibility that makes remote and cross-border work attractive also creates classification risk when businesses adopt a one-size-fits-all contractor model. Laws and enforcement are moving in the opposite direction: toward greater protection for economically dependent workers and more responsibility for companies that benefit from their labour.

For leaders building international teams, the challenge is to integrate classification into strategic planning rather than treat it as a late-stage HR formality. That may mean accepting higher upfront costs for proper employment in some markets, using EOR structures thoughtfully, and reserving contractor models for genuinely independent, project-based work. It also means coordinating legal, HR, finance, and operations so that classification decisions are consistent with the company's broader economy, employment, and sustainable growth objectives. As international rules continue to evolve, organizations that invest early in robust classification frameworks, transparent practices, and informed management are likely to face fewer surprises-and be better positioned to compete for global talent on stable, compliant terms. This feature is complete, but the broader topic has much more to offer. Keep looking beyond the surface and following the details that matter.

What Falling Producer Prices Mean for Business Margins

Last updated by Editorial team at upbizinfo.com on Wednesday 21 October 2026
Article Image for What Falling Producer Prices Mean for Business Margins

What Falling Producer Prices Really Mean for Business Margins

When producer prices start to fall, many headlines quickly frame it as "disinflation" or even a win for consumers. For businesses, the story is more complicated. Changes in producer prices ripple through supply chains, pricing strategies, investment plans, and ultimately profit margins. Understanding how and when falling input costs help-or hurt-margins is now a core management skill, especially after several years of volatile inflation across major economies.

This page examines what declining producer prices typically signal, how they feed into business margins in different sectors, and what leaders can do to protect profitability when the Producer Price Index (PPI) is moving down rather than up.

What producer prices actually measure-and why they matter

Producer price indices track the prices that businesses receive (output prices) and often the prices they pay (input prices) for goods and, increasingly, some services. In the United States, the Producer Price Index compiled by the Bureau of Labor Statistics (BLS) is the most-cited measure, while many other countries publish similar indicators through their national statistics offices. Globally, organizations such as the OECD (oecd.org) and Eurostat (ec.europa.eu) aggregate and compare producer price trends across economies.

For management teams tracking business conditions, producer prices matter because they sit between raw commodity costs and final consumer prices. They are often more volatile than consumer price indices (CPI), reacting earlier to shifts in energy prices, exchange rates, supply-chain disruptions, and global demand. When producer prices fall, it can mean lower input costs, lower selling prices, or both, depending on where a company sits in the value chain.

PPI data are also closely watched by central banks such as the Federal Reserve (federalreserve.gov) and the European Central Bank (ecb.europa.eu) as an early signal of inflation or disinflation pressures. As a result, sustained declines in producer prices can influence interest-rate expectations, which in turn affect financing costs and investment decisions for businesses.

Falling producer prices: disinflation, deflation, or just normalization?

Before drawing conclusions for margins, it helps to understand what is driving producer prices lower. There are three broad scenarios, each with very different implications for profitability.

In the first scenario, producer prices fall because earlier supply shocks are unwinding. For example, the surge in energy, freight, and industrial input prices seen in 2021-2022 has partly reversed as supply chains normalized and demand rotated. In this case, falling producer prices can represent a "normalization" of costs from unusually high levels. Margins may actually improve if companies are able to lower their own input costs while keeping selling prices relatively stable, at least for a period. This kind of disinflation is usually positive for markets and business confidence.

In the second scenario, producer prices fall because demand is weakening. When global manufacturing slows, as signaled by purchasing managers' indices tracked by organizations like S&P Global (spglobal.com), producers often cut prices to keep order books full. Here, falling PPI can be a symptom of broader economic softness. While input costs may decline, volume and pricing power can deteriorate faster, putting pressure on margins. This is particularly relevant for cyclical sectors such as metals, chemicals, automotive components, and capital goods.

The third, more severe scenario is outright deflationary pressure. If producer prices are falling sharply and persistently across a wide range of sectors, it may indicate an economy flirting with deflation, as Japan did for parts of the 1990s and 2000s. In such an environment, customers may delay purchases in anticipation of lower prices, and debt burdens become more painful in real terms. Even if input costs are falling, it becomes extremely difficult for businesses to maintain margins when both prices and volumes are under sustained pressure.

For decision-makers, the key is not just that producer prices are falling, but why they are falling, how broad-based the decline is, and whether it is expected to persist.

How falling input costs can expand margins-when conditions are right

On the positive side, falling producer prices often mean cheaper inputs. For manufacturers, construction firms, logistics providers, and many service businesses, lower prices for energy, materials, components, and transport can significantly reduce the cost of goods sold (COGS) and operating expenses.

If companies are able to maintain their selling prices while their own input costs decline, gross margins can expand. This margin expansion is more likely when:

The company has strong brand power or differentiated offerings, so customers are less sensitive to short-term cost changes.

Contracts with customers are fixed-price or adjust slowly, while procurement contracts are more flexible.

Competitors are constrained-by capacity, regulation, or weaker balance sheets-and therefore slower to pass on cost savings.

Consumer-facing brands in sectors like packaged goods, personal care, or niche electronics sometimes enjoy this dynamic. When commodity prices fall from a spike, they may keep retail prices steady, at least temporarily, effectively "banking" the difference as higher margins. The same can occur in B2B services where pricing is based on value delivered rather than a direct pass-through of input costs.

From an investment perspective, this is why equity analysts at firms such as Goldman Sachs (goldmansachs.com) or Morgan Stanley (morganstanley.com) often talk about "margin tailwinds" when producer and commodity prices ease after a period of stress. For businesses with pricing power and relatively flexible procurement, falling producer prices can indeed be a tailwind for profitability.

However, this favorable window is rarely permanent. Competitive pressure, customer renegotiations, and procurement transparency increasingly compress the lag between cost reductions and price concessions. Digital marketplaces and more sophisticated purchasing teams mean buyers often know when suppliers' input costs are falling. The challenge for management is to use any temporary margin windfall strategically rather than assuming it will last.

When falling producer prices squeeze instead of support margins

The same decline in producer prices can be damaging when companies are forced to cut selling prices faster than their own costs fall. This is particularly common in commoditized industries, where prices are set in competitive markets and passing through cost movements is almost automatic.

Producers of basic materials-such as steel, petrochemicals, and agricultural commodities-are often price takers. When global benchmarks fall, they receive lower prices immediately, while their own cost base (labor, energy contracts, debt servicing) may adjust only slowly. In this case, gross margins can compress sharply even if some input costs are easing. Similar dynamics affect many manufacturers that sell into highly competitive OEM or retail supply chains where buyers can quickly switch to alternative suppliers.

Exporters face an additional layer of complexity when exchange rates move alongside producer prices. A stronger domestic currency can reduce imported input costs but also makes exports less competitive. Central banks and institutions like the International Monetary Fund (imf.org) frequently highlight how currency swings can amplify or offset PPI movements, especially in open economies.

There is also a timing issue. If a company agreed to long-term supply contracts at high prices, it may be locked into elevated input costs even as market prices fall. Meanwhile, customers may insist on price reductions linked to spot or index levels. This mismatch can produce a period of intense margin compression until contracts are renegotiated or expire.

For businesses with significant fixed costs, falling producer prices tied to weaker demand can be particularly painful. Lower selling prices and reduced volumes both work against the ability to cover fixed overheads, pushing down operating margins and return on capital. This is often when management teams turn to cost-cutting, capacity reductions, or restructuring-moves that can stabilize margins but may also constrain future growth if overdone.

Sector-by-sector: who tends to win and lose?

The impact of falling producer prices varies widely by sector and position in the value chain. Looking across world and regional data, several broad patterns emerge.

In energy-intensive sectors such as metals, cement, glass, and certain chemicals, lower energy and feedstock prices can be a major positive, provided end-market demand holds up. However, if falling producer prices reflect a broader industrial slowdown, these sectors can quickly swing from benefiting to suffering as capacity utilization drops.

Consumer goods manufacturers may see mixed effects. Those with strong brands and differentiated products can often keep prices steady for longer when input costs fall, supporting margins. In contrast, private-label and low-cost producers selling into large retailers usually have less pricing power; buyers will demand cost pass-through, limiting margin upside.

Technology and digital businesses are somewhat insulated from direct producer price movements, as their cost structures are more dominated by labor, R&D, and cloud or data-center services. However, they can still be affected indirectly through changes in customer investment budgets, financing conditions, and wage dynamics. For example, an industrial software provider may see weaker demand if manufacturing clients are cutting capex in response to lower producer prices and softer order books.

Service sectors like logistics and transportation are heavily exposed to fuel prices but often operate with fuel surcharges or index-based contracts. When fuel and other producer prices fall, margins can improve temporarily if surcharges lag. Over time, though, competitive forces generally compress this advantage.

Retailers and wholesalers sit at the end of the chain and may benefit when producer prices fall but consumer prices remain sticky. Supermarkets, for instance, can enjoy better gross margins if they negotiate lower prices from suppliers while maintaining shelf prices. However, in highly competitive retail markets, particularly online, price comparison and promotional pressure can quickly erode this benefit.

Implications for pricing, contracts, and negotiation strategy

For leadership teams, falling producer prices are a signal to revisit pricing architecture, contract design, and negotiation posture rather than simply reacting to cost changes on a case-by-case basis.

On the pricing side, companies need clarity on which products or services are cost-plus, which are value-based, and where they have genuine pricing power. In cost-plus segments, customers will expect quick pass-through of lower input costs, and resisting this can damage relationships. In value-based segments, there may be more room to hold prices, especially if the offering is tied to outcomes rather than inputs. A structured pricing strategy, often supported by data and analytics, can help identify where margin can be protected without losing volume.

Contract terms are equally important. Indexation clauses that link prices to specific producer price indices, commodity benchmarks, or energy prices can reduce negotiation friction but may also limit flexibility. When PPI is falling, customers may push for more aggressive indexation, while suppliers may want caps, floors, or longer averaging periods to smooth volatility. Legal and procurement teams should collaborate closely with finance and sales to ensure contract structures align with the company's risk appetite and margin objectives.

Negotiation strategy also changes in a falling PPI environment. Buyers will arrive at the table armed with public data from sources such as the World Bank (worldbank.org) or national statistics offices, showing declines in relevant indices. Sellers need their own fact base, including the share of total costs represented by indexed inputs, the timing of their own contract renewals with suppliers, and any offsetting cost pressures (for example, wages, regulatory compliance, or financing). Transparent, data-driven negotiation can preserve relationships while still protecting a fair share of margin.

Cash flow, investment, and financing: second-order effects

Falling producer prices do not only affect operating margins; they also influence cash flow, investment timing, and financing conditions. In many cases, these second-order effects matter as much as the immediate change in gross margin.

On the cash-flow side, lower input costs can reduce working capital needs, especially for businesses with large inventories of raw materials or work-in-progress. Companies may be able to run leaner inventories if price volatility subsides, freeing up cash for debt reduction, investment, or shareholder returns. However, if falling producer prices reflect weaker demand, receivables may grow more slowly or even decline, and customers' payment behavior can deteriorate.

Investment decisions also shift. When producer prices fall in a context of easing inflation and interest rates, as monitored by central banks and institutions like the Bank for International Settlements (bis.org), borrowing costs may decline, encouraging capital expenditure. Yet if management interprets falling PPI as a sign of looming recession, they may postpone or scale back projects, prioritizing balance-sheet resilience over expansion. The same indicator can therefore trigger very different responses depending on the perceived macro narrative.

For highly leveraged companies, deflationary or disinflationary environments can be double-edged. Lower interest rates may reduce financing costs, but if nominal revenue growth slows or turns negative, debt ratios can worsen. Lenders and rating agencies will pay close attention to how management plans to defend margins in a weaker pricing environment. Firms that can show credible cost management, pricing discipline, and realistic volume forecasts will generally find it easier to refinance on acceptable terms.

Strategy for business leaders: making falling producer prices work for you

For executives, the central question is not whether producer prices are rising or falling, but how to adapt strategy so that margin performance is resilient across cycles. Several practical priorities stand out.

First, invest in better cost and margin visibility. Finance and operations teams should be able to break down unit economics by product, customer, and region, showing how specific input prices feed into margins. Without this granularity, management will struggle to distinguish where falling producer prices genuinely create room for margin expansion from where they must be passed through.

Second, build more flexible supply chains and procurement arrangements. Diversifying suppliers, renegotiating indexation terms, and shortening contract durations in volatile categories can help businesses capture more upside when producer prices fall while limiting downside when they rise. This is particularly relevant after the supply-chain shocks of recent years, which many business leaders are still recalibrating.

Third, strengthen pricing capabilities. This includes not only headline prices but also discounting policies, surcharges, and value-based pricing models. Companies that rely on ad hoc discounting and reactive negotiations tend to give away margin quickly when producer prices move. Those with clear guardrails, approval processes, and data-backed pricing tools are better able to defend profitability.

Fourth, align cost management with strategic priorities. It can be tempting to treat a period of falling producer prices as an excuse to relax on efficiency. Yet structural cost improvements-automation, process redesign, digitization-are often most affordable and least disruptive when input cost pressure is easing. Linking such initiatives to broader new technology and productivity strategies can position the business for stronger margins when the cycle turns again.

Finally, communicate clearly with stakeholders. Employees, investors, lenders, and major customers will all have their own interpretations of what falling producer prices mean. Transparent communication about how management sees the macro environment, what it implies for pricing and investment, and how the company intends to protect margins can build trust and reduce uncertainty.

Reading producer price signals with nuance

Producer prices are a powerful but blunt instrument. A headline number-"PPI down 1.5% year-on-year"-says little on its own about an individual company's prospects. For some, it may herald a welcome easing of cost pressures and a chance to rebuild margins after an inflationary shock. For others, it may be an early warning of weaker demand, intensifying price competition, and a need to rethink capacity and cost structures.

For leaders across manufacturing, services, banking, and other sectors, the task is to read these signals with nuance: to understand the drivers behind falling producer prices, map them to their own cost and revenue structures, and respond with deliberate adjustments rather than reflexive cuts or concessions. Businesses that treat PPI movements as one input into a broader strategic dashboard-alongside customer behavior, competitive dynamics, and financial resilience-are better placed to protect and, where possible, enhance margins through the next phase of the economic cycle.

Business Loan Covenants Explained for Growing Companies

Last updated by Editorial team at upbizinfo.com on Tuesday 20 October 2026
Article Image for Business Loan Covenants Explained for Growing Companies

Business Loan Covenants Explained for Growing Companies

When a growing company negotiates a bank loan or private credit facility, the headline items-interest rate, term, and collateral-tend to dominate attention. Yet for many borrowers, the real constraints and risks sit in the fine print: the loan covenants. These contractual promises can quietly shape everything from hiring plans and dividend policy to whether a future funding round is even possible. Understanding how covenants work, what is negotiable, and how to manage them in practice has become increasingly important as lenders worldwide tighten standards and focus more heavily on risk. This page unpacks the main types of business loan covenants, why lenders insist on them, how they affect growth-stage companies in particular, and what management teams can do to negotiate and monitor them more effectively.

What loan covenants are and why lenders use them

Loan covenants are contractual conditions that a borrower agrees to follow as part of a credit agreement. They sit alongside core economic terms such as principal, interest, maturity, and security. In essence, covenants are early-warning and risk-control tools: they give lenders visibility into a borrower's performance and the power to intervene before a problem turns into a payment default.

Commercial banks, development finance institutions, and private credit funds all rely heavily on covenants. After the global financial crisis and subsequent regulatory reforms, supervisors such as the Bank for International Settlements and national regulators like the U.S. Federal Reserve and European Central Bank pushed banks to improve credit risk management, which has reinforced the use of structured covenant packages. At the same time, private credit markets-where bespoke covenants are the norm-have become a major source of funding for mid-market and sponsor-backed deals.

For growing companies, especially those without long credit histories or hard collateral, covenants often function as a substitute for physical security. A lender that is taking a view on future cash flows or intangible assets will typically demand tighter information rights and performance triggers. That can be constructive, imposing discipline on financial management, but it can also constrain strategic flexibility if not carefully calibrated.

The three main categories: affirmative, negative, and financial covenants

Although covenant language can be dense and highly customized, most provisions fall into three broad categories. Understanding this basic structure makes it easier to read term sheets and prioritize negotiation.

Affirmative (or positive) covenants

Affirmative covenants are things the borrower must actively do. They are often operational or reporting obligations and, while they may feel routine, they are legally binding.

Common examples include obligations to:

Provide periodic financial statements and management accounts.

Maintain proper books and records in accordance with applicable accounting standards.

Comply with all relevant laws, including tax, employment, and environmental regulations.

Maintain insurance coverage at agreed levels.

Pay all taxes when due.

Notify the lender promptly of material adverse events, litigation, or regulatory actions.

For a growth-stage business, these covenants can push the company to professionalize its finance function earlier than it otherwise might. Quarterly or monthly reporting, covenant calculations, and board-level dashboards become essential. This is often aligned with good practice for scaling companies and can support better decision-making around business growth and strategy.

Negative covenants

Negative covenants restrict what the borrower can do without lender consent. They are central to how lenders protect their position against actions that could weaken credit quality or reduce recoveries in a downside scenario.

Typical negative covenants include limits or prohibitions on:

Incurring additional debt beyond defined baskets or ratios.

Granting liens or security interests to other creditors.

Paying dividends or making distributions to shareholders.

Making acquisitions, investments, or asset sales above agreed thresholds.

Entering into mergers, consolidations, or changes of control.

Changing the nature of the business or disposing of key assets.

For high-growth companies, negative covenants can be especially sensitive. Restrictions on additional indebtedness, for example, may limit the ability to stack venture debt facilities or raise working capital lines from other banks. Change-of-control provisions can complicate future equity rounds or exits. Non-compete style limitations on changing the business line may conflict with a startup's natural tendency to pivot. These are precisely the areas where founders and CFOs need to engage early and ensure covenants are tailored to the company's realistic growth plans.

Financial (maintenance and incurrence) covenants

Financial covenants link the loan to quantitative metrics. They are often the most closely monitored provisions and, if breached, can trigger default even when payments are current.

There are two broad types:

Maintenance covenants require the borrower to maintain certain financial ratios or thresholds at all times or at regular testing dates (for example, quarterly). They are common in traditional bank lending and leveraged finance.

Incurrence covenants only apply when the borrower takes a specific action, such as incurring new debt or making a distribution. They are more common in high-yield bond markets and some "covenant-lite" loans.

Common financial covenant metrics include:

Leverage ratio (total debt to EBITDA).

Interest coverage ratio (EBITDA to interest expense).

Fixed charge coverage ratio (cash flow to fixed charges such as rent, interest, and scheduled amortization).

Minimum EBITDA or revenue thresholds.

Minimum liquidity or cash balance.

Net worth or tangible net worth tests.

For companies in cyclical sectors or early-stage businesses with volatile earnings, maintenance covenants tied closely to EBITDA can be challenging. Even a temporary downturn or investment phase can push ratios out of compliance. That is why many lenders now use a mix of liquidity tests and more flexible earnings measures, and why borrowers often seek headroom and cure rights.

How covenants affect growing companies in practice

Covenants do not exist in isolation; they interact with a company's strategic agenda, capital structure, and operational realities. For growth-oriented businesses, several themes recur across markets and sectors.

First, covenants influence how quickly a company can scale. Restrictions on capital expenditure, acquisitions, or additional borrowing can slow expansion plans. For example, a regional services business looking to roll up smaller competitors may be constrained by debt-to-EBITDA limits that do not fully account for post-integration synergies. Similarly, a manufacturer investing heavily in automation may breach fixed charge coverage ratios in the near term even though the project strengthens long-term competitiveness. Working closely with lenders to build these scenarios into the covenant design is essential.

Second, covenants shape equity and investment strategy. Venture-backed companies increasingly use growth debt alongside equity to extend runway. However, typical negative covenants around change of control, preferred payments, and additional liens can conflict with later-stage equity rounds or convertible instruments. Investors may insist on "debt-friendly" term sheet language or require that certain covenants be waived in connection with new funding. Aligning lender and investor expectations early reduces the risk of last-minute renegotiations that can derail transactions.

Third, covenants affect operational resilience. Minimum liquidity requirements, for instance, can act as a guardrail against over-extension, forcing management to maintain a cash buffer. Frequent reporting covenants can highlight deteriorating margins or working capital issues earlier than they might otherwise be spotted. In that sense, well-designed covenants can support sound banking relationships and internal governance rather than simply acting as constraints.

Finally, covenants carry reputational and relationship implications. A covenant breach, even if quickly cured, can undermine lender confidence and make future borrowing more expensive. In some jurisdictions, covenant defaults must be disclosed in financial statements, which can affect counterparties and potential investors. This is one reason many corporate treasurers treat covenant headroom and forecasting as core risk-management tasks rather than administrative chores.

Typical covenants in different types of business loans

While every loan agreement is negotiated, patterns do emerge by product type and lender category. Understanding these patterns can help growing companies benchmark offers and anticipate trade-offs.

In traditional bank term loans and revolving credit facilities, especially those provided by relationship banks to mid-market corporates, covenant packages typically include a mix of information undertakings, negative covenants on additional debt and security, and two or three core maintenance ratios. Banks regulated under frameworks such as Basel III and Basel IV often prefer this structure because it supports internal risk ratings and regulatory capital models. As a result, covenant flexibility may be limited, but pricing can be relatively attractive compared with more opportunistic financing.

Asset-based lending (ABL) and receivables finance, by contrast, rely more on the value and performance of specific assets. Here, covenants focus heavily on borrowing base calculations, collateral eligibility criteria, concentration limits, and regular reporting of receivables or inventory. Financial maintenance covenants may be lighter or focused on liquidity. For fast-growing businesses with strong working capital assets but uneven profitability, ABL can offer a useful alternative, though it demands robust operational systems and controls.

In the private credit and direct lending space, covenant structures vary widely. Some funds offer "covenant-lite" or incurrence-based deals that resemble high-yield bonds, especially for sponsor-backed borrowers with diversified earnings. Others, particularly those focused on smaller or riskier credits, use tight maintenance covenants and detailed business-plan milestones. Because private credit is less standardized and more relationship-driven, borrowers often have more room to tailor covenants to their specific growth plans, but they may pay higher interest margins in return.

Finally, government-backed loans and guarantee schemes-such as those supported by development banks or export credit agencies-can introduce unique covenants around local content, sustainability, or employment. Institutions like the World Bank Group, International Finance Corporation (IFC), and regional development banks increasingly embed environmental, social, and governance (ESG) requirements into their credit documentation. For companies targeting sustainable growth, these covenants can align with broader sustainability commitments, but they may also require new reporting capabilities.

Key concepts: headroom, baskets, and carve-outs

Beyond the headline ratios and restrictions, much of the practical flexibility in a loan agreement comes from three structural concepts: headroom, baskets, and carve-outs. Understanding and negotiating these elements can significantly reduce the risk of accidental covenant breaches.

Headroom refers to the buffer between the company's expected performance and the covenant threshold. For example, if a loan requires a maximum leverage ratio of 3.5x and the company's business plan projects leverage of 3.0x, the headroom is 0.5 turns. Lenders and borrowers both know that forecasts are rarely perfect, so sensible headroom is essential. Sophisticated borrowers stress-test their financial models under downside scenarios and seek covenant levels that they can meet even if revenue growth slows or margins compress.

Baskets are defined allowances within negative covenants that permit certain actions up to a specified limit without triggering a breach. A debt basket might allow the company to incur a modest amount of additional unsecured debt, for example, or to finance equipment leases. Investment baskets may allow minority stakes in joint ventures or strategic partnerships. For growing companies, baskets around small acquisitions, intra-group loans, and working-capital facilities can be especially important.

Carve-outs are exceptions to otherwise broad restrictions. A negative covenant might prohibit granting security interests "other than" certain permitted liens, such as statutory liens, purchase-money security interests, or existing mortgages. Carve-outs allow the business to operate normally-paying taxes, leasing equipment, dealing with suppliers-without constantly seeking lender consent. The balance between broad prohibitions and carefully drafted carve-outs often determines how workable a covenant package is in day-to-day operations.

Negotiating covenants: what growing companies should focus on

When negotiating a loan, management teams naturally focus on interest margins and loan size. Yet for many growth-stage borrowers, the long-term impact of covenants can be just as significant. A few practical priorities tend to matter across sectors and geographies.

First, align covenants with the business plan. That means building integrated financial models that reflect realistic growth, seasonality, and investment needs, then mapping these against proposed covenant ratios and restrictions. Scenario analysis-testing downside cases such as delayed product launches, cost overruns, or macroeconomic shocks-helps identify where covenants may be too tight. Companies that can show lenders robust planning, informed by credible market data from sources like the OECD, IMF, or national statistics agencies, are better positioned to negotiate.

Second, anticipate future funding needs. If the company expects to raise additional equity, venture debt, or working capital lines, the loan agreement should leave room for this. That may mean negotiating baskets for additional debt, clarifying how subordinated shareholder loans are treated, or ensuring that change-of-control provisions do not unintentionally capture new minority investors. Coordination between the CFO, legal counsel, and existing investors is crucial to avoid conflicts between loan covenants and shareholder agreements.

Third, pay attention to definitions and calculation mechanics. Many covenant disputes arise not from the headline ratios but from how terms like "EBITDA," "net debt," or "cash" are defined. Adjustments for exceptional items, pro forma earnings from acquisitions, and treatment of leases can all materially impact compliance. Engaging experienced counsel and, where appropriate, auditors or advisers from firms such as PwC, KPMG, Deloitte, or EY can help ensure definitions are fair and aligned with the company's reporting practices.

Fourth, consider cure rights and waiver processes. Equity cure provisions, which allow shareholders to inject capital to remedy a covenant breach, can be valuable in volatile sectors. So can grace periods, materiality thresholds for defaults, and clear procedures for requesting waivers. While lenders will resist anything that undermines the protective value of covenants, they often recognize the importance of giving fundamentally sound businesses a path to recover from temporary setbacks.

Finally, evaluate the full package rather than individual clauses in isolation. A slightly tighter leverage covenant might be acceptable if accompanied by generous baskets and robust cure rights; conversely, a seemingly benign ratio could be problematic if paired with rigid definitions and limited headroom. Comparing offers from different lenders on a holistic basis, including non-price terms, is essential. This is an area where independent business and banking advisers can add substantial value.

Monitoring and managing covenants once the loan is in place

Signing the loan agreement is only the beginning. Effective covenant management is an ongoing process that touches finance, operations, and governance. Companies that treat covenants as a living risk-management framework, rather than a static legal document, are better placed to avoid surprises.

A good starting point is building a covenant calendar and dashboard. The finance team should track all reporting deadlines, testing dates, and notice requirements, ensuring that responsibilities are clearly assigned. Many mid-market businesses now use treasury management systems or integrated ERP tools to automate data collection and ratio calculations, reducing the risk of error. Regular internal reporting to the board or investment committee, incorporating covenant metrics alongside operating KPIs, helps keep the topic visible.

Forecasting is equally important. Rather than testing covenants only at quarter-end, forward-looking companies project compliance across the life of the loan, updating scenarios as new information emerges. This is especially relevant for businesses exposed to macroeconomic volatility, where changes in interest rates, foreign exchange, or input costs can quickly affect coverage ratios. Central bank guidance from institutions such as the Bank of England, European Central Bank, and Federal Reserve can provide useful context for planning interest-rate scenarios.

Communication with lenders plays a critical role. If forecasts suggest that a covenant breach is possible, early engagement is almost always preferable to waiting until the last minute. Lenders are more likely to grant waivers or temporary resets when they feel informed, trust management, and see a credible plan to restore compliance. Conversely, surprises can damage relationships and trigger defensive behavior, including tighter controls or higher pricing at renewal.

Internally, covenant management can drive stronger financial discipline. For example, minimum liquidity covenants may encourage more conservative working-capital policies, while leverage limits can shape dividend decisions. Linking management incentives to covenant-relevant metrics-such as cash generation or interest coverage-can align behavior with the company's long-term financial resilience. Articles and top resources on corporate finance, employment, and management often highlight how this kind of alignment supports sustainable growth.

Covenant breaches: consequences and options

Despite best efforts, covenant breaches do occur. Understanding the potential consequences and available responses helps management teams react calmly and pragmatically when issues arise.

Legally, a covenant breach is typically an event of default, giving the lender the right-but not always the obligation-to accelerate the loan, demand immediate repayment, increase pricing, or enforce security. In practice, especially in relationship-driven corporate banking, lenders often prefer to negotiate waivers or amendments rather than push a viable borrower into distress. Regulatory and reputational considerations, highlighted by bodies like the Financial Stability Board and national supervisors, also encourage constructive workout approaches where feasible.

The immediate steps following a potential breach usually include confirming the calculations, assessing materiality, and engaging legal and financial advisers. If the breach is technical (for example, a late delivery of financial statements) and quickly remediable, a simple waiver letter may suffice. If it is financial-such as a leverage ratio failure-more substantial discussions may be needed around business plans, additional equity, asset sales, or revised covenants.

From a strategic perspective, a breach can be a catalyst for deeper changes. It may prompt a reassessment of the company's capital structure, leading to equity injections, refinancing, or a shift toward less leveraged growth. It can also drive operational restructuring, cost reductions, or portfolio rationalization. While these measures are rarely comfortable, they can ultimately strengthen the business if approached with transparency and realism.

For founders and executives, the key is to treat covenants as early-warning signals rather than merely legal tripwires. Timely recognition of pressure points, supported by robust data and open dialogue with lenders, often creates more room for constructive solutions than last-minute crisis management.

Integrating covenants into long-term growth strategy

For many growing companies, especially those transitioning from startup to scale-up, the first significant bank loan or private credit facility marks a turning point. It signals that the business has moved beyond purely equity-funded experimentation into a phase where leverage, markets, and disciplined financial management matter. In that context, loan covenants are not just constraints; they are part of the broader architecture of corporate governance and risk control.

Integrating covenant thinking into strategic planning means more than checking ratios in a spreadsheet. It involves aligning product roadmaps, hiring plans, capex programs, and M&A ambitions with a realistic view of what the balance sheet can support. It also means building a finance function capable of high-quality forecasting, scenario analysis, and stakeholder communication. As digital tools, data analytics, and even AI-driven forecasting become more accessible, mid-market companies have new opportunities to manage these complexities with sophistication once reserved for large corporates.

In global credit markets that remain sensitive to shocks-from interest-rate cycles and geopolitical tensions to sector-specific disruptions-lenders are unlikely to abandon covenants any time soon. If anything, scrutiny is increasing. For growth-oriented businesses, the most effective response is not to resist covenants outright, but to understand them deeply, negotiate them intelligently, and use them as a framework for sustainable, well-governed expansion.

For leaders shaping their next financing round, that means treating covenant discussions with the same seriousness as valuation, pricing, and headline loan size. Done well, the result is not just a signed agreement, but a long-term partnership with lenders that supports the company's ambitions across business cycles and into new markets and technologies.

How to Build a Business Operating Plan That Teams Actually Use

Last updated by Editorial team at upbizinfo.com on Monday 19 October 2026
Article Image for How to Build a Business Operating Plan That Teams Actually Use

How to Build a Business Operating Plan That Teams Actually Use

Most leaders do not struggle to create operating plans; they struggle to get anyone to follow them. Slide decks gather dust, spreadsheets drift out of date, and "the plan" becomes something people reference only at annual reviews. The real challenge is building a business operating plan that is clear enough to guide daily decisions, flexible enough to adapt, and practical enough that teams actually use it. This rather important write-up focuses on that practical side: how to design, communicate, and maintain an operating plan that lives in the business instead of in a binder.

What a Business Operating Plan Really Is (And Isn't)

A business operating plan sits between strategy and execution. Strategy defines where the company is going and why. The operating plan defines how it will get there this year: what will be done, by whom, by when, and with what resources.

A useful operating plan typically translates strategic goals into a small set of measurable outcomes, then breaks those down into initiatives, responsibilities, budgets, and operating rhythms. It is more detailed than a strategy document, but more stable and higher-level than a weekly task list or project plan.

Many organizations confuse an annual budget, a list of projects, or a set of marketing campaigns with an operating plan. Budget spreadsheets from tools like Microsoft Excel or Google Sheets and project boards in tools such as Trello or Asana are important, but they are artifacts of the plan, not the plan itself. A real operating plan connects money, people, priorities, and time into a coherent picture that every team can see themselves in.

For leaders and founders, this is where execution discipline begins. Without a credible, shared operating plan, discussions about performance, hiring, investment, and even technology adoption-from core systems to emerging areas like AI-quickly become ad hoc and political rather than data-driven.

Why Most Operating Plans Fail in Practice

If operating plans are so important, why are they so often ignored? Across startups, mid-market firms, and large enterprises, the same failure patterns recur.

One common problem is over-complexity. In an attempt to be thorough, leadership teams produce plans packed with dozens of goals, metrics, and initiatives. This might impress a board or lender, but it overwhelms the teams expected to execute. Research from organizations like McKinsey & Company and Bain & Company has repeatedly highlighted that companies which ruthlessly prioritize a small number of initiatives tend to outperform those that spread effort thinly across many. When everything is a priority, nothing is.

Another problem is misalignment between the plan and how the business truly operates. For example, a sales-led company might create a plan dominated by product and technology milestones while leaving sales and customer success as afterthoughts. Or a global firm might draft a plan centrally that ignores local market realities. In both cases, teams quickly default to "how we've always done things," because the plan does not reflect their real constraints, incentives, or workflows.

A third failure mode is static planning in a dynamic environment. Many companies still treat the operating plan as a once-a-year event, even though markets, customer behavior, and funding conditions can shift within months. Modern planning frameworks promoted by firms like OKR specialists and strategy consultancies-drawing on agile and lean principles-emphasize shorter planning cycles and frequent reviews. Without that adaptability, teams stop updating the plan the moment reality diverges.

Finally, culture and incentives matter. If performance conversations, promotions, and recognition are not anchored in the operating plan, people will treat it as optional. This is where HR and leadership practices intersect with planning: organizations that integrate the plan into how they manage performance, allocate budgets, and communicate with investors are far more likely to see teams use it daily.

Start with a Clear Strategic Spine

An operating plan that people use starts with ruthless clarity about what truly matters. Before diving into templates and tools, leadership teams need to define a strategic spine: a simple, coherent set of outcomes that will define success for the year.

A useful starting point is to articulate three to five company-level objectives that directly support the longer-term strategy. These should be outcome-focused, not activity-focused. For example, "increase net revenue retention to 110%" is clearer and more actionable than "improve customer success," because it implies specific levers for product, sales, and operations. Organizations that use frameworks like Objectives and Key Results (OKRs), popularized by practitioners and platforms such as Google, Atlassian, and Workday, often find this discipline helpful.

From there, each objective should have a small set of key results: measurable indicators that signal progress. These can be financial (revenue, margin), customer-centric (NPS, churn), operational (cycle time, defect rates), or people-related (engagement, regretted attrition). External resources like Harvard Business Review, MIT Sloan Management Review, and Strategy& provide evidence-backed guidance on choosing robust metrics.

This strategic spine is not the full operating plan, but it is the anchor. Every function-sales, marketing, product, operations, finance, HR-should be able to trace its own goals and initiatives directly back to these company-level outcomes. When that line of sight is missing, plans fragment into siloed wish lists.

Readers who want a deeper grounding in strategy and execution linkages may find it useful to explore broader coverage of business fundamentals and economy dynamics, as these shape what is realistic in any given year.

Translate Strategy into a Practical Operating Blueprint

Once the strategic spine is clear, the task becomes translation: turning high-level objectives into a practical blueprint that guides daily work. This is where many plans drift into either vague aspirations or micromanaging detail. The goal instead is to define just enough structure that teams can make consistent decisions without losing autonomy.

A pragmatic operating blueprint typically covers several dimensions. First, it defines annual and quarterly targets for key metrics, broken down by region, business unit, or product line where relevant. Finance teams often lead this process, drawing on forecasting techniques and tools endorsed by bodies like the CFA Institute or AICPA, but it should not be a finance-only exercise. Commercial and operations leaders must co-own the assumptions.

Second, the blueprint identifies the major initiatives required to hit those targets. These are not every task, but the big rocks: product launches, market expansions, infrastructure upgrades, hiring ramps, cost-optimization programs, or technology transformations such as implementing new banking platforms or AI-powered tools. Each initiative should have a clear owner, a defined scope, timing, and an explicit link to one or more key results.

Third, capacity and constraints must be made explicit. Many operating plans quietly assume unlimited engineering time, sales capacity, or marketing budget. A credible blueprint quantifies what is actually available: headcount, capital expenditure, vendor capacity, and regulatory constraints. Guidance from institutions like the World Bank, OECD, and national regulators (for example, the U.S. Small Business Administration or UK's Companies House via GOV.UK) can help organizations understand market and regulatory realities that affect capacity, especially for cross-border operations.

Finally, the blueprint defines operating rhythms: the cadences for business reviews, forecast updates, cross-functional meetings, and decision-making. For instance, a monthly performance review and a quarterly strategic review, with clearly defined inputs and outputs, can prevent the plan from becoming static. Companies adopting agile or lean approaches, as described by organizations like Scrum.org and Scaled Agile, often find that shorter cycles improve accountability and learning.

At this stage, it is useful to connect the blueprint to other domains of the business. For example, hiring and workforce planning should align with the company's employment strategy, while capital allocation to new ventures or expansions may intersect with investment priorities.

Co-Create the Plan with the People Who Must Execute It

The fastest way to ensure a plan is ignored is to write it in a small executive circle and then "roll it out" as a finished product. Teams use plans they helped create. Co-creation does not mean planning by committee; it means structured involvement of the people closest to customers, operations, and technology.

A practical approach is to use a cascading but iterative process. Leadership defines the strategic spine and initial constraints. Functions then draft their own sub-plans-objectives, key results, initiatives, and resource needs-within those constraints. These drafts are brought back together in cross-functional sessions to resolve conflicts, dependencies, and overlaps. The result is a plan that reflects ground realities and cross-team coordination.

Organizations with distributed or remote workforces can use digital collaboration tools such as Miro, Notion, or Microsoft Teams to facilitate this co-creation. The key is transparency: assumptions, trade-offs, and rejected options should be visible, not hidden in side conversations. This builds trust and makes it easier to adjust the plan later without people feeling blindsided.

Involving frontline teams early also surfaces operational risks that might otherwise be missed. For example, a plan to expand into new markets may require adjustments to marketing localization, customer support hours, or compliance processes. Similarly, a decision to adopt AI-based tools may require upskilling, change management, and careful attention to ethical and regulatory standards, as highlighted by bodies like the OECD and European Commission.

For growing companies and founders, this co-creation process can be particularly powerful. It reinforces a culture where strategy and execution are shared responsibilities, not something dictated from the top. Leaders who have scaled startups in ecosystems like Y Combinator or Techstars often emphasize this collaborative discipline as a key factor in maintaining alignment during rapid growth.

Make the Plan Radically Simple to Understand

Even the most thoughtful operating plan fails if people cannot easily understand it. Simplicity here does not mean dumbing things down; it means designing the plan so that any team member can answer three questions: What are we trying to achieve? How does my team contribute? How will we know if we are on track?

One effective practice is to create a single-page or one-slide summary of the plan: company objectives, key results, and the top five to seven cross-functional initiatives. This "plan on a page" becomes the reference point for all-hands meetings, performance reviews, and investor discussions. Detailed plans, budgets, and project roadmaps then sit underneath it for those who need them.

Visuals help. Strategy maps, value stream maps, and simple swimlane diagrams can show how work flows across teams. Organizations can draw on frameworks from sources like Balanced Scorecard Institute, Prosci, or Lean Enterprise Institute to design these visuals. The goal is not to adopt a specific methodology, but to create clarity: who does what, in what sequence, with what handoffs.

Language also matters. Avoid jargon that varies across departments. If "pipeline," "churn," or "margin" mean different things to sales, finance, and product, the plan will be interpreted differently. Standardizing definitions-sometimes through a simple data dictionary maintained by finance or analytics teams-prevents misunderstandings. Data governance best practices from organizations like DAMA International or EDM Council can be adapted even in smaller firms.

Finally, connect the plan to stories, not just numbers. Leaders who explain the plan through customer narratives, competitive scenarios, or concrete examples make it easier for teams to internalize. For instance, instead of saying "we will reduce cycle time by 15%," a leader might frame it as "customers will go from waiting three days to one day for onboarding," linking the metric to a real experience.

Tie the Plan Directly to Budgets, People, and Incentives

Teams take plans seriously when they see that money, headcount, and performance evaluations are aligned with them. An operating plan that is disconnected from the budget is effectively optional.

Finance and HR leaders play a central role here. Budget allocations should explicitly reference the initiatives and objectives in the plan. If an initiative is on the plan but unfunded, it is not a real priority. Conversely, if significant spending is planned for areas not mentioned in the operating plan, that misalignment should be challenged. Guidance from professional bodies such as CIMA, CFA Institute, and national finance associations can help organizations adopt robust budgeting and forecasting practices.

Performance management should also reference the plan. Individual and team goals-whether framed as OKRs, KPIs, or another system-should map directly to the operating plan's objectives and key results. Many organizations use HR platforms such as Workday, SAP SuccessFactors, or BambooHR to embed this alignment into goal-setting and review cycles.

Incentive structures, including bonuses and sales commissions, should be transparent about how they relate to the plan. For instance, if the company's operating plan emphasizes sustainable growth and profitability, but sales incentives reward top-line revenue at any cost, teams will naturally follow the money rather than the plan. Organizations focused on sustainable business practices are particularly attuned to this alignment between financial and non-financial metrics.

This is also a good moment to ensure compliance with labor and employment regulations in key markets, drawing on resources from agencies like the U.S. Department of Labor, the UK's ACAS, and counterparts across Europe and Asia. Misaligned or opaque incentives can create legal as well as cultural risks.

Build Operating Rhythms That Keep the Plan Alive

A plan that is not reviewed regularly will drift out of relevance. Operating rhythms-recurring meetings, reports, and decision forums-are what keep the plan alive and embedded in daily work.

At the company level, many organizations adopt a monthly or six-week business review cycle. These sessions focus on a small set of indicators tied to the operating plan: revenue, pipeline, churn, product delivery, operational performance, and key people metrics. The goal is not to rehash every metric, but to identify where performance is off track and agree on specific corrective actions. Publications like Harvard Business Review and McKinsey Quarterly have documented how high-performing organizations use such reviews to drive disciplined execution.

At the functional and team levels, weekly or biweekly check-ins can connect local work to the broader plan. Agile ceremonies such as sprint reviews and retrospectives, when anchored in the operating plan's key results rather than purely technical goals, help teams see how their work contributes. This is especially important in product and engineering organizations, where technical roadmaps can drift away from customer and commercial priorities.

Technology can support these rhythms. Business intelligence tools like Tableau, Power BI, or Looker can create dashboards that mirror the structure of the operating plan, making progress visible to everyone. Collaboration platforms such as Slack, Microsoft Teams, or Google Workspace can host channels or spaces dedicated to tracking specific objectives or initiatives.

However, tools do not replace discipline. Leaders must consistently reference the operating plan in their communications: town halls, investor updates, and board meetings. When decisions deviate from the plan, the rationale should be explained. This transparency keeps the plan credible and teaches teams how to adapt it when conditions change, such as shifts in markets or macroeconomic headwinds covered in broader news and world analyses.

Keep the Plan Adaptive Without Losing Focus

In volatile environments, a static annual plan can quickly become obsolete. Yet constant change can also create confusion and planning fatigue. The art is to design an operating plan that is stable at the level of objectives and flexible at the level of tactics.

One approach is to treat the annual operating plan as a hypothesis rather than a commitment carved in stone. Quarterly reviews then become opportunities to update assumptions, reallocate resources, and adjust initiatives while preserving the core objectives. This is analogous to portfolio management in investing, where asset allocations are periodically rebalanced in response to market conditions, a practice explained by institutions like Vanguard, BlackRock, and Morningstar.

Scenario planning can also be useful, especially in sectors exposed to regulatory shifts, geopolitical risk, or technological disruption. Organizations like the World Economic Forum and OECD publish scenarios and trend analyses that can help businesses think about alternative futures. Instead of building one detailed plan, leadership teams can define a base case plus a small number of plausible alternatives, with trigger points that would prompt a shift from one scenario to another.

For smaller businesses and startups, adaptability often means being explicit about what will be stopped or slowed when new opportunities arise. Without this discipline, every new idea becomes an additional project layered on top of an already-full plan, leading to burnout and diluted impact. Founders and executives should be willing to say, "We will only take on this new initiative if we pause or cancel another one," and record those decisions in the operating plan.

An adaptive plan also needs good data. Reliable, timely information on financials, customer behavior, and operational performance is essential. This may involve investing in better analytics infrastructure or data governance. For companies operating in regulated industries like banking or crypto, it also means ensuring that data practices comply with standards from regulators such as the U.S. SEC, European Central Bank, or national financial authorities.

Embed the Plan into Culture and Communication

Ultimately, teams use plans when they see them as part of the company's identity and daily language. This is where culture and communication play a decisive role.

Leaders should model the behavior they want to see. When executives make decisions, they should explicitly reference how those decisions align with (or intentionally diverge from) the operating plan. When celebrating wins, they should connect achievements back to the plan's objectives and key results. This signals that the plan is not a bureaucratic requirement but the backbone of how the company thinks.

Storytelling helps embed the plan culturally. Managers can share concrete examples of how teams used the plan to make trade-offs, say no to lower-priority work, or coordinate across departments. These stories can be shared in all-hands meetings, internal newsletters, or collaboration channels. They demonstrate that the plan is a tool for empowerment, not surveillance.

Training and onboarding also matter. New hires should be introduced to the operating plan early, not months after joining. Understanding how the company sets priorities and measures success is as critical as learning products or systems. Resources from organizations like SHRM, CIPD, and leading business schools can help HR and L&D teams design effective onboarding around strategy and execution.

Finally, feedback loops should be built in. Teams should have channels to question assumptions, propose adjustments, and flag when parts of the plan are no longer realistic. This can be done through periodic surveys, open Q&A sessions, or structured retrospectives. When leaders listen and adjust, the plan becomes a living contract rather than a one-way directive.

Bringing It All Together!

A business operating plan that teams actually use is not defined by the elegance of its spreadsheets or the sophistication of its templates. It is defined by clarity, co-creation, alignment, and rhythm. It starts with a simple strategic spine, translates that into a practical blueprint tied to budgets and people, and is kept alive through regular review and open communication.

For leaders, founders, and managers across sectors-from technology and finance to manufacturing and services-the payoff is substantial. A good operating plan reduces noise, accelerates decision-making, and makes it easier to navigate uncertainty in global markets and economies. More importantly, it gives teams a shared language for what matters now and how their work contributes.

The test is straightforward: if any employee can explain the company's main objectives for the year, how their team supports them, and how progress is tracked, then the operating plan is doing its job. If not, the opportunity is clear-to rebuild the plan not as a document for executives, but as a daily guide for everyone who makes the business work.

How Corporate Treasury Supports Financial Stability

Last updated by Editorial team at upbizinfo.com on Sunday 18 October 2026
Article Image for How Corporate Treasury Supports Financial Stability

How Corporate Treasury Supports Financial Stability

Corporate Treasury at the Center of Modern Business Resilience

Corporate leaders across North America, Europe, Asia and beyond increasingly recognize that financial stability is no longer a passive outcome of strong performance, but an actively managed capability in which corporate treasury plays a central, strategic role. For the growing readership here, from fast-growing technology ventures in Singapore, established industrial champions in Germany, financial institutions in the United States and United Kingdom, and diversified conglomerates in markets from Brazil to South Africa, the evolution of treasury from back-office function to strategic co-pilot has become a defining feature of resilient business models. As volatility in interest rates, foreign exchange, supply chains and geopolitical conditions continues to test balance sheets, the way treasury is organized, governed and integrated into decision-making has become a core driver of financial stability, investor confidence and long-term value creation.

While traditional descriptions framed treasury as the department that "manages cash," leading organizations in 2026 see it as the guardian of liquidity, risk and capital structure, operating at the intersection of finance, technology and strategy. This evolution is particularly visible in sectors where global operations, complex funding structures and digital transformation converge, such as multinational manufacturers, cross-border e-commerce platforms, global banks and high-growth technology companies. For readers seeking a structured view of how this transformation fits into broader corporate finance and strategy, the dedicated pages on business fundamentals and banking and treasury relationships provide additional context and case-driven perspectives.

Liquidity Management as the First Line of Financial Defense

At the heart of corporate financial stability lies the ability to meet obligations in full and on time, even under stress, and this is where corporate treasury's mandate around liquidity management is most visible. Treasury teams in leading companies now operate sophisticated cash visibility frameworks that consolidate global bank balances, intercompany positions and short-term investments in real time or near real time, reducing the historical reliance on static, end-of-month snapshots. By using modern treasury management systems and application programming interfaces with global banks, treasurers can dynamically adjust funding, investment and payment decisions across entities in the United States, Europe, Asia and other regions, thereby minimizing idle cash, reducing overdraft costs and ensuring that critical operations in markets such as China, India or Brazil are never constrained by avoidable liquidity bottlenecks.

This level of control has become especially important in an era of persistent macroeconomic uncertainty, where central banks from the Federal Reserve in the United States to the European Central Bank in the euro area and the Bank of England in the United Kingdom have had to respond to inflationary pressures, financial market stress and geopolitical disruptions with frequent policy adjustments. Treasurers who follow developments through trusted sources such as the Bank for International Settlements and International Monetary Fund are better positioned to anticipate shifts in funding conditions and adjust their internal liquidity buffers accordingly. For readers of upbizinfo.com interested in the macro backdrop that shapes these decisions, the economy insights section offers up-to-date analysis of inflation, growth and monetary policy trends across major regions.

Capital Structure, Funding Strategy and Banking Relationships

Financial stability also depends on how companies structure their balance sheets and access capital, and corporate treasury is the function that translates high-level capital structure targets into concrete funding strategies. In 2026, leading organizations in the United States, Europe, Asia and Australia increasingly rely on a diversified mix of bank loans, public bonds, private placements, securitizations and, in some cases, hybrid instruments, carefully calibrated to their cash flow profiles, risk appetite and credit ratings. Treasury teams work closely with chief financial officers and boards to model different leverage scenarios, assess interest rate and refinancing risks, and determine the appropriate balance between fixed and floating rate exposure, often using derivatives to fine-tune profiles in response to changing market conditions.

The quality and depth of banking relationships is a critical enabler of this funding resilience. Corporate treasurers maintain structured dialogue with relationship banks across global financial centers such as New York, London, Frankfurt, Singapore and Hong Kong, ensuring access to committed credit facilities, trade finance, cash management solutions and capital markets execution. Institutions such as JPMorgan Chase, HSBC, BNP Paribas, Deutsche Bank and Standard Chartered increasingly position their corporate and investment banking offerings as integrated platforms, and sophisticated treasury teams evaluate them not only on pricing but also on balance sheet strength, digital connectivity and crisis-time support. For decision-makers seeking to deepen their understanding of global capital markets, resources like the World Bank and OECD corporate finance analysis provide valuable context on trends in corporate leverage, bond issuance and banking sector resilience.

Within upbizinfo.com, executives can connect these capital structure considerations with broader investment strategy discussions, particularly around how treasury's funding choices influence the feasibility and timing of strategic acquisitions, greenfield projects and technology investments across regions from North America to Southeast Asia.

Risk Management: From Currency and Interest Rates to Counterparty and Systemic Risk

Corporate treasury's contribution to financial stability extends well beyond liquidity and funding into the domain of risk management, where it often serves as the first line of defense against market, credit and operational risks that could destabilize earnings, cash flows or solvency. Among the most visible responsibilities is the management of foreign exchange risk, particularly for multinational companies generating revenue in multiple currencies such as the US dollar, euro, pound sterling, Japanese yen, Chinese renminbi and various emerging market currencies. Treasurers design hedging strategies using forwards, options and swaps to smooth the translation and transaction impacts of currency movements, aligning hedge ratios with board-approved policies and risk appetite. They also coordinate closely with business units to ensure that commercial contracts, pricing structures and procurement arrangements do not inadvertently create unhedged exposures that could undermine margins.

Interest rate risk management has become equally critical in the wake of the rapid tightening cycles observed in major economies since the early 2020s. Corporate treasurers monitor yield curves, credit spreads and central bank communications, frequently consulting analysis from sources such as the Bank of England and European Central Bank to inform decisions on refinancing, fixed-floating mixes and hedging strategies. They also assess counterparty risk across banks, money market funds and other financial institutions, using internal credit assessments and external ratings from organizations like S&P Global Ratings, Moody's and Fitch Ratings, and they implement concentration limits and collateral arrangements to mitigate potential contagion effects in times of stress.

For readers interested in how these risk management practices intersect with broader global developments, the world and markets coverage and markets analysis on upbizinfo.com provide a bridge between macro events and treasury-level implications, helping executives in regions from Canada and Switzerland to South Korea and New Zealand contextualize their own risk exposures.

The Strategic Role of Treasury in Corporate Planning and Investment

As corporate boards and executive committees in 2026 place greater emphasis on resilience, scenario planning and capital discipline, treasury has moved from a reactive, transactional role to a proactive, strategic partner in corporate planning. Treasurers increasingly participate in long-term business planning, mergers and acquisitions evaluations, capital expenditure prioritization and portfolio optimization, providing a financial stability lens on strategic options. By modeling the impact of different growth strategies, geographic expansions or divestitures on liquidity, leverage, credit ratings and covenant headroom, treasury teams help organizations avoid strategies that might look attractive on paper but carry unacceptable financial fragility under plausible downside scenarios.

This strategic integration is particularly important for high-growth founders and scale-ups in technology, fintech, renewable energy and advanced manufacturing, many of whom form part of the upbizinfo.com readership. For these companies, treasury capabilities often need to mature quickly as they transition from venture-backed growth to public markets or institutional debt financing, where investors and lenders expect robust treasury governance and risk management. The founders and growth stories section of upbizinfo.com highlights how visionary leaders in markets such as the United States, United Kingdom, Germany, Singapore and Australia increasingly view treasury as a strategic asset rather than a cost center, investing in experienced talent, systems and processes earlier in their corporate journeys.

External resources such as Harvard Business Review and McKinsey & Company have published extensive research on how finance functions can shape strategic resilience, and many of the best practices identified there-from integrated planning to dynamic resource allocation-are now being operationalized through modern treasury capabilities.

Employment, Skills and the Professionalization of Treasury

The elevation of treasury's role has important implications for employment, skills and career paths, both for established professionals and for the next generation of finance talent across Europe, Asia, North America, Africa and South America. In 2026, treasury teams are increasingly multidisciplinary, combining traditional finance and accounting expertise with quantitative analysis, technology fluency, regulatory knowledge and strategic communication skills. Employers in leading markets such as the United States, United Kingdom, Germany, Singapore and the Netherlands now seek treasurers who can interpret complex macroeconomic developments, design sophisticated hedging strategies, collaborate with banks and investors, and communicate scenarios and recommendations clearly to boards and rating agencies.

Professional bodies such as the Association for Financial Professionals (AFP), Association of Corporate Treasurers (ACT) and EuroFinance have responded by expanding certification programs, conferences and thought leadership focused on digital treasury, risk management and strategic business partnering. For readers exploring treasury-related career opportunities or planning organizational staffing, the employment-focused content at jobs and careers and employment trends on upbizinfo.com offers additional insights into evolving role definitions, compensation benchmarks and regional talent dynamics.

Trusted external resources, including the AFP and ACT, provide detailed competency frameworks and continuing education pathways that help finance professionals in Canada, France, Italy, Spain, South Africa, Malaysia and other markets align their skills with the expectations of modern treasury organizations.

Technology, AI and the Digital Treasury in 2026

Digital transformation has reshaped corporate treasury perhaps more profoundly than any other finance function, and by 2026, the notion of a "digital treasury" is no longer aspirational but an operational reality for leading organizations. Modern treasury management systems integrate seamlessly with enterprise resource planning platforms, banking portals, payment networks and data analytics tools, enabling treasurers to access real-time data on cash, exposures and counterparties across regions as diverse as Japan, Thailand, Norway and Brazil. Advanced analytics, including machine learning techniques, are increasingly used to forecast cash flows, detect anomalies in payments, optimize investment portfolios and simulate the impact of stress scenarios on liquidity and covenant compliance.

Artificial intelligence has become particularly valuable in enhancing forecasting accuracy, scenario modeling and decision support. By ingesting large volumes of internal transaction data and external indicators-such as interest rates, commodity prices, foreign exchange rates and macroeconomic indicators-AI-driven tools can help treasurers identify patterns, anticipate risks and evaluate complex trade-offs more quickly than traditional spreadsheet-based approaches. However, responsible deployment requires robust data governance, model validation and human oversight to ensure that AI augments rather than replaces professional judgment, particularly in high-stakes decisions related to funding, hedging and counterparty limits.

Executives seeking to understand how AI is reshaping finance and treasury can explore the dedicated AI and automation and technology innovation sections of upbizinfo.com, which examine both the opportunities and the governance challenges associated with embedding intelligent systems into core financial processes. External perspectives from organizations such as the World Economic Forum and Deloitte further illuminate how digital treasury capabilities contribute to enterprise-wide resilience and competitiveness.

The Role of Treasury in Sustainable Finance and ESG Integration

Sustainability and environmental, social and governance (ESG) considerations have become central to corporate strategy in 2026, and treasury is now a key execution arm for translating ESG commitments into financial structures, instruments and risk frameworks. Many companies in Europe, North America and Asia Pacific have issued green, social or sustainability-linked bonds, whose proceeds are allocated to projects such as renewable energy, energy-efficient buildings, sustainable supply chains and social impact initiatives. Treasury teams are responsible for structuring these instruments, engaging with investors, ensuring alignment with recognized taxonomies and principles, and reporting transparently on the use of proceeds and impact metrics.

In parallel, treasurers are integrating ESG criteria into investment policies for surplus cash, increasingly favoring money market funds, bank deposits and fixed income instruments issued by counterparties with strong sustainability profiles. They also work with procurement, operations and risk functions to assess the financial implications of climate risk, carbon pricing, regulatory changes and evolving stakeholder expectations, particularly in sectors with high environmental footprints such as energy, transport, manufacturing and agriculture. Resources such as the Task Force on Climate-related Financial Disclosures and UN Principles for Responsible Investment provide frameworks that many treasury teams use to align their practices with emerging global standards.

For the upbizinfo.com audience, which increasingly views sustainability as a driver of long-term business value rather than a compliance obligation, the sustainable business and ESG section offers practical insights into how treasury can support decarbonization, inclusive growth and resilience agendas, while maintaining rigorous financial discipline and risk management.

Crypto, Digital Assets and the Cautious Expansion of the Treasury Toolkit

The rise of cryptoassets and digital currencies over the past decade has prompted intense debate within corporate finance circles, and by 2026, corporate treasury's approach to these instruments has evolved from experimental curiosity to cautious, policy-driven engagement. While most large corporations remain conservative in their direct exposure to volatile cryptocurrencies, some have begun to explore tokenized deposits, regulated stablecoins and central bank digital currency pilots as potential tools for improving cross-border payment efficiency, liquidity management and working capital optimization, particularly in trade corridors spanning Asia, Europe and the Americas.

Treasury teams evaluating these opportunities must navigate complex regulatory landscapes, cybersecurity risks, accounting treatment questions and volatility considerations, all while ensuring that any adoption supports rather than undermines financial stability. They increasingly rely on guidance from regulators such as the US Securities and Exchange Commission, European Securities and Markets Authority and Monetary Authority of Singapore, as well as analysis from institutions like the Bank for International Settlements Innovation Hub, to shape their policies. For organizations and professionals looking to stay informed on this rapidly evolving domain, the crypto and digital assets coverage on upbizinfo.com provides curated insights into both opportunities and risks, grounded in a financial stability perspective.

Treasury's Influence on Corporate Reputation, Governance and Trust

Beyond the technical dimensions of liquidity, funding, risk and technology, corporate treasury plays an important role in shaping stakeholder trust, corporate reputation and governance quality. Investors, rating agencies, regulators, employees and business partners increasingly scrutinize how companies manage their financial resources, respond to crises and communicate about risks and resilience. Treasury's ability to maintain strong liquidity buffers, avoid covenant breaches, meet obligations during stress, and provide transparent, data-driven disclosures reinforces perceptions of prudence and reliability, which in turn can lower funding costs, attract long-term investors and support strategic flexibility.

Effective treasury governance involves clear policies on risk appetite, hedging, counterparty exposure, investment of surplus cash, use of derivatives and engagement with banks and capital markets. It also requires robust internal controls, segregation of duties, audit trails and compliance with evolving regulatory requirements across jurisdictions. Organizations that align treasury governance with broader corporate governance frameworks, as articulated by bodies such as the OECD Corporate Governance Principles, are better positioned to demonstrate that financial stability is embedded in their culture and decision-making, rather than treated as an afterthought.

For the global business audience of upbizinfo.com, which includes board members, executives, founders and senior managers from the United States, United Kingdom, Germany, Canada, Australia, France, Italy, Spain, Netherlands, Switzerland, China, Singapore, South Korea, Japan and beyond, these governance and trust dimensions are increasingly central to strategic dialogue, investor relations and risk oversight.

The Outlook: Treasury as an Anchor for Global Businesses

The convergence of macroeconomic uncertainty, technological disruption, regulatory evolution and shifting stakeholder expectations continues to test the resilience of businesses across all major regions, from North America and Europe to Asia, Africa and South America. In this environment, corporate treasury emerges not merely as a functional necessity but as a strategic anchor that supports financial stability, enables agile decision-making and underpins long-term value creation. Organizations that invest in modern treasury capabilities-combining experienced professionals, advanced systems, robust governance and strong external partnerships-are better equipped to navigate shocks, seize opportunities and sustain competitiveness.

For readers online today, the themes explored here intersect with many of the platform's core reporting areas, from banking and financial services and global business strategy to technology and AI, investment and capital markets and sustainable growth. By approaching corporate treasury not as a narrow specialist function but as an integrated, forward-looking partner in strategy, risk and transformation, companies all over global markets can strengthen their financial foundations and build the resilience required to thrive in an increasingly complex world.

Executives, founders and finance leaders who engage with the evolving role of treasury-leveraging insights from trusted global institutions such as the International Monetary Fund, World Bank, Bank for International Settlements and leading professional associations-will be well placed to ensure that financial stability is not left to chance, but is actively designed, monitored and reinforced at the core of their organizations. In doing so, they align with the central mission of upbizinfo.com: to equip decision-makers with the insight, context and practical understanding needed to build stronger, more resilient and more sustainable businesses in every major region of the world.

The Future of Enterprise Software for Business Growth

Last updated by Editorial team at upbizinfo.com on Saturday 17 October 2026
Article Image for The Future of Enterprise Software for Business Growth

The Future of Enterprise Software for Business Growth

A New Era of Enterprise Software!

Finally enterprise software has moved from being a back-office enabler to a central strategic asset that shapes how organizations compete, innovate, and grow, and for the business audience here, spanning North America, Europe, Asia-Pacific, Africa, and South America, this shift is redefining how leaders think about business models, operating structures, and technology investment, particularly as they seek resilience in volatile markets and consistent value creation across diverse regulatory and cultural environments. Where enterprise platforms once focused primarily on standardizing processes and cutting costs, the modern landscape is increasingly oriented toward intelligent automation, data-driven decision-making, hyper-personalized customer experiences, and agile collaboration, with business leaders recognizing that their software stack is now deeply intertwined with their strategy for revenue growth, margin expansion, and competitive differentiation. As organizations all over navigate rising regulatory scrutiny, rapid advances in artificial intelligence and cloud computing, and intensifying expectations from both customers and employees, enterprise software is evolving into a flexible, composable layer that connects finance, operations, marketing, human capital, and innovation into a coherent digital fabric that can adapt at the speed of change.

For decision-makers following our new coverage of business strategy and transformation, the future of enterprise software is not an abstract technology discussion but a practical question of how to architect systems that allow for continuous experimentation, faster time to market, and more accurate forecasting in an environment where economic cycles are shorter and shocks are more frequent. This evolution is visible in the way leading enterprises are integrating advanced analytics into their core processes, rethinking their approach to enterprise resource planning, and adopting industry-specific platforms that blend financial, operational, and customer data into actionable insight, with growth-focused leaders paying particular attention to how software can support international expansion, cross-border compliance, and scalable operating models that work equally well in the United States, Germany, Singapore, and Brazil. As enterprise software becomes more intelligent, modular, and outcome-oriented, it is also becoming a primary lens through which boards and executives evaluate their organization's readiness for the next decade of competition.

Strategic Drivers: Growth, Resilience, and Productivity

The dominant strategic drivers behind the next generation of enterprise software are growth, resilience, and productivity, and each of these priorities is being reshaped by digital capabilities that simply did not exist at scale a decade ago. Growth is no longer viewed only as revenue expansion; instead, it encompasses the ability to launch new products faster, enter new geographies with lower friction, and orchestrate complex partner ecosystems that span continents and industries, with enterprise software providing the data, workflow, and governance backbone that makes such orchestration possible. Resilience has moved to the forefront following a sequence of global disruptions, including pandemic-era supply chain shocks, geopolitical tensions, and energy price volatility, and organizations now demand software that can simulate scenarios, stress-test operations, and support rapid reconfiguration of suppliers, production sites, and distribution networks across regions such as Europe, Asia, and North America. Productivity, meanwhile, is being redefined through automation and augmentation rather than simple headcount reduction, with advanced digital tools empowering employees in finance, operations, marketing, and customer service to focus on higher-value activities while software takes on repetitive, error-prone tasks.

Global institutions such as the World Economic Forum have highlighted how digitalization and automation are transforming labor markets and growth models, and executives monitoring these trends increasingly see enterprise platforms as central to their strategy rather than as isolated IT projects. Learn more about how digital transformation is reshaping competitiveness at the World Economic Forum. At the same time, regulators and policymakers in jurisdictions like the European Union, the United States, and Asia-Pacific are refining rules on data privacy, cybersecurity, and AI governance, which means that enterprise software must embed compliance and risk management into its core design instead of treating them as afterthoughts. For the readers here watching global economic developments, this alignment of technology, regulation, and strategy underscores why the future of enterprise software is a board-level issue, touching everything from capital allocation to workforce planning and international expansion.

Cloud-Native and Composable Architectures as Growth Engines

One of the most significant shifts in enterprise software over the past few years has been the widespread adoption of cloud-native and composable architectures, which are now foundational to how growth-oriented companies design and operate their digital capabilities. Instead of relying on monolithic applications that are difficult to update and customize, organizations increasingly favor modular platforms, microservices, and APIs that allow them to assemble best-of-breed capabilities, integrate specialized tools, and swap components without disrupting the entire system. This composable approach is particularly attractive to businesses operating across multiple countries and industries, where regulatory requirements, customer preferences, and local market dynamics can vary widely, and where agility in adapting processes for markets such as the United States, Germany, Singapore, or Brazil can be a decisive competitive advantage. Cloud-native platforms also offer elastic scalability, enabling enterprises to handle seasonal spikes, international rollouts, and data-intensive analytics without the capital expenditure and operational complexity traditionally associated with on-premises infrastructure.

Industry leaders such as Microsoft, Amazon Web Services, and Google Cloud have accelerated this transition by offering robust cloud ecosystems that support advanced analytics, machine learning, and industry-specific solutions, alongside strong security and compliance frameworks that appeal to regulated sectors like banking, healthcare, and public services. For organizations evaluating their options, resources from Gartner provide insight into the evolution of cloud and enterprise application markets, helping CIOs and CFOs align their technology roadmaps with business goals; executives can explore current trends and Magic Quadrant analyses at Gartner. For the business audience of upbizinfo.com, particularly those considering how to modernize legacy systems and integrate emerging technologies, cloud-native and composable architectures represent more than an IT modernization initiative; they are a structural shift that enables faster innovation cycles, more efficient capital deployment, and a more resilient foundation for international growth.

AI-Driven Enterprise Platforms and Intelligent Automation

By 2026, artificial intelligence has become deeply embedded in enterprise software, moving far beyond isolated pilots and proofs of concept to become a pervasive layer that informs decision-making, automates complex workflows, and personalizes interactions across the value chain. In finance and banking, AI-driven platforms are analyzing transaction patterns, credit histories, and macroeconomic indicators to improve risk assessment, fraud detection, and portfolio optimization, while in operations and supply chain management, machine learning models are forecasting demand, optimizing inventory, and reducing logistics costs across regions from Europe to Asia-Pacific. Within human resources and talent management, AI is being used to identify skills gaps, recommend learning pathways, and support more objective hiring and promotion decisions, with many organizations using predictive analytics to anticipate workforce needs and design more flexible employment models. For leaders tracking these developments through the new features of AI in business, the key shift is that AI is no longer a peripheral tool but a core capability embedded in enterprise platforms and workflows.

The rise of generative AI and large language models has further expanded the possibilities for intelligent automation, enabling software to draft reports, summarize complex datasets, generate code, and support natural language interactions between employees and enterprise systems. Organizations that once struggled with fragmented data and siloed knowledge are now deploying AI-powered assistants that can surface insights from across finance, operations, marketing, and customer service, making it easier for decision-makers to access relevant information quickly. Research from McKinsey & Company has documented the potential productivity gains from generative AI, particularly in knowledge-intensive functions such as software development, customer operations, and marketing; executives can explore these findings at McKinsey. For enterprises focused on growth, the strategic question is how to integrate AI into their core platforms in a way that enhances human judgment, preserves transparency, and aligns with regulatory expectations, rather than pursuing automation for its own sake. As AI capabilities become more accessible through cloud platforms and enterprise software suites, the differentiator increasingly lies in how effectively organizations design processes, governance, and culture to harness these tools for sustained value creation.

Enterprise Software for Banking, Finance, and the New Digital Economy

The banking and financial services sectors have been at the forefront of enterprise software transformation, and by 2026, this transformation is reshaping how institutions compete, collaborate, and manage risk. Traditional banks in the United States, the United Kingdom, Germany, and Singapore, facing competition from agile fintechs and digital-only challengers, are investing heavily in modern core banking platforms, cloud-based risk and compliance systems, and AI-enhanced customer experience tools that enable personalized financial advice, real-time credit decisions, and seamless omnichannel interactions. For readers following upbizinfo.com's insights on banking innovation, the trajectory is clear: financial institutions that successfully modernize their software foundations can launch new products faster, respond more flexibly to regulatory changes, and leverage data to deepen customer relationships across retail, corporate, and wealth management segments.

At the same time, the broader digital economy, including digital payments, embedded finance, and decentralized finance experiments, is driving demand for enterprise platforms that can integrate with a complex ecosystem of partners, regulators, and technology providers. Organizations exploring digital assets and blockchain-based solutions are deploying specialized platforms to manage custody, compliance, and transaction monitoring, while regulators and standard-setting bodies are refining frameworks to ensure stability and consumer protection. Learn more about how global financial systems are evolving at the Bank for International Settlements. For business leaders assessing how to participate in this evolving landscape, the priority is to select enterprise software that can support both current regulatory obligations and potential future models, including tokenized assets, programmable money, and cross-border digital payment schemes. Within this context, our pages of investment trends and crypto developments offers a complementary perspective on how enterprise software is enabling new financial products and business models that were not feasible under legacy systems.

Impact on Employment, Skills, and the Future of Work

The transformation of enterprise software has profound implications for employment, skills, and the future of work, and leaders across industries are recalibrating their talent strategies to reflect the new digital reality. Automation and AI-driven workflows are reducing the need for repetitive, rules-based tasks in areas such as data entry, basic transaction processing, and routine reporting, while simultaneously creating demand for new roles in data science, process design, AI governance, cybersecurity, and digital product management. In markets such as the United States, Germany, India, and Brazil, employers are recognizing that successful adoption of modern enterprise platforms depends as much on workforce capabilities and change management as on technology investment, and they are increasingly partnering with educational institutions, training providers, and internal academies to reskill employees at scale. For readers of upbizinfo.com interested in employment trends and jobs of the future, the central theme is that enterprise software is not simply displacing work; it is reshaping the nature of work and the capabilities required to thrive.

Global organizations like the International Labour Organization and the OECD have emphasized the importance of lifelong learning and digital skills development to ensure that workers can adapt to rapidly changing technologies and job requirements, and their research highlights both opportunities and risks across advanced and emerging economies. Learn more about global labor market trends at the International Labour Organization and explore skills-focused insights at the OECD. For enterprises, the practical challenge is to design software-enabled processes that complement human strengths, provide clear pathways for skill development, and maintain employee engagement during periods of significant change. This involves close coordination between HR, IT, and business leaders, as well as transparent communication about how new systems will affect roles, performance expectations, and career progression. Organizations that approach enterprise software transformation as a holistic workforce initiative, rather than as a purely technical project, are better positioned to build a resilient, adaptable talent base that can sustain growth in an era of continual technological disruption.

Founders, Scale-Ups, and the New Enterprise Software Ecosystem

For founders and scale-up leaders, particularly those in innovation hubs across the United States, the United Kingdom, Germany, France, Singapore, and Australia, the evolving enterprise software landscape presents both unprecedented opportunities and heightened competitive pressures. On one hand, the rise of cloud-native platforms, open APIs, and low-code tools has dramatically lowered the barriers to building and deploying sophisticated business applications, enabling start-ups to serve global customers and integrate with large enterprises far more quickly than in previous generations. On the other hand, the expectations of corporate buyers have increased, with procurement teams demanding robust security, compliance, interoperability, and long-term support from even relatively young vendors. For readers engaging with events of founders and entrepreneurial journeys, the key insight is that success in the enterprise software space now requires a combination of product excellence, domain expertise, and credibility in areas such as data governance and regulatory alignment.

Venture capital and private equity investors are paying close attention to enterprise software ventures that can demonstrate not only strong growth metrics but also sustainable unit economics, low churn, and clear paths to profitability, particularly in an environment of rising interest rates and more selective funding. Organizations such as Crunchbase and PitchBook provide visibility into funding trends, valuations, and exit activity, which can help founders benchmark their progress and refine their strategies in line with investor expectations; interested readers can explore data-driven insights at PitchBook. For scale-ups aiming to serve multinational clients, building early capabilities in localization, compliance, and integration with major cloud providers and enterprise platforms is increasingly essential. As the ecosystem matures, partnerships between established technology giants and innovative start-ups are becoming a common route to market, with large enterprises seeking specialized capabilities while maintaining a stable core platform. This collaborative model is reshaping how enterprise software innovation reaches end-users, and it underscores the importance of ecosystem thinking for founders who aspire to global relevance.

Global and Regional Dynamics in Enterprise Software Adoption

Enterprise software adoption is not uniform across regions, and understanding these differences is crucial for organizations operating globally or planning international expansion. In North America and parts of Western Europe, cloud adoption and digital transformation are relatively advanced, with many large enterprises having already migrated significant workloads to the cloud and now focusing on optimizing their architectures, integrating AI capabilities, and refining data governance. In contrast, some regions in Asia, Africa, and Latin America are experiencing a leapfrogging effect, where organizations adopt modern, cloud-native solutions without the burden of extensive legacy systems, enabling them to move quickly in areas such as mobile-first customer engagement, digital payments, and platform-based business models. For readers of upbizinfo.com interested in global business developments, these regional patterns shape both competitive dynamics and partnership opportunities, as companies seek to balance global standardization with local responsiveness.

Policy environments and regulatory frameworks also vary significantly, influencing how enterprise software is designed and deployed. The European Union's evolving data protection and AI regulations, including the General Data Protection Regulation (GDPR) and the emerging AI Act, are setting stringent standards for transparency, accountability, and data handling, which in turn affect global software vendors that operate in or serve European markets. Learn more about European digital regulation at the European Commission. Meanwhile, countries like Singapore and South Korea are positioning themselves as innovation-friendly digital hubs, offering incentives for cloud adoption, AI experimentation, and cross-border data flows under robust cybersecurity standards. For multinational enterprises, this means that their software strategies must account for a complex web of legal, cultural, and infrastructural factors, and that selecting platforms with strong multi-region compliance capabilities is no longer optional but essential. As reporting here frequently emphasizes, growth in a globalized economy increasingly depends on the ability to navigate these regional nuances while maintaining a coherent, scalable digital backbone.

Data, Analytics, and the Quest for Real-Time Insight

At the heart of modern enterprise software lies data, and organizations across industries are intensifying their efforts to turn vast volumes of operational, financial, and customer information into timely, actionable insight. In 2026, leading enterprises are moving beyond traditional business intelligence dashboards to embrace real-time analytics, predictive modeling, and prescriptive recommendations that are embedded directly into workflows and decision points. This shift is evident in areas such as supply chain visibility, where real-time tracking and predictive risk alerts help companies anticipate disruptions; in marketing, where customer behavior data informs personalized campaigns across channels; and in financial planning, where scenario modeling supports more agile budgeting and capital allocation. For the business community following upbizinfo.com's coverage of markets and economic signals, the capacity to interpret and act on data quickly is increasingly seen as a core driver of competitive advantage.

Global standards bodies and industry groups are working to improve data interoperability and governance, recognizing that fragmented, inconsistent data remains a major barrier to effective analytics in many organizations. Resources from the ISO and sector-specific consortia provide frameworks for data quality, security, and sharing that can guide enterprise data strategies; more information on international standards can be found at the International Organization for Standardization. For enterprises, the practical challenge lies in building data architectures that can integrate information from legacy systems, cloud platforms, partner ecosystems, and external sources, while maintaining robust controls over access, privacy, and usage. Modern enterprise software is increasingly designed with these requirements in mind, offering built-in data catalogs, lineage tracking, and governance tools that support both compliance and innovation. As organizations continue to refine their analytics capabilities, the emphasis is shifting from simply collecting data to cultivating a culture of data literacy and evidence-based decision-making at every level of the business.

Sustainability, Governance, and Responsible Digital Growth

Sustainability and responsible governance have become central considerations in enterprise software strategy, as stakeholders ranging from regulators and investors to customers and employees demand greater transparency and accountability in how organizations operate and grow. Environmental, social, and governance (ESG) reporting is increasingly mandated or strongly encouraged in many jurisdictions, and enterprises are turning to specialized software solutions to track emissions, resource usage, supply chain practices, and social impact metrics across complex global operations. For readers of upbizinfo.com exploring sustainable business practices, it is clear that modern enterprise platforms are evolving to embed ESG considerations directly into planning, procurement, and performance management processes, rather than treating them as standalone reporting exercises. This integration allows companies to make more informed trade-offs between financial performance and sustainability goals, and to demonstrate progress to stakeholders with greater credibility.

International organizations such as the United Nations and the Global Reporting Initiative have played a significant role in shaping sustainability frameworks and reporting standards, which in turn influence how enterprise software vendors design their ESG modules and data models. Learn more about global sustainability goals at the United Nations and explore reporting standards at the Global Reporting Initiative. For businesses, the convergence of regulatory expectations, investor scrutiny, and societal pressure means that responsible digital growth is no longer optional; it is a prerequisite for long-term viability and access to capital. Enterprise software that can provide transparent, auditable data on environmental and social performance, while supporting ethical AI practices, data privacy, and cybersecurity, will be increasingly favored by organizations seeking to align their growth strategies with broader societal objectives. For the audience of upbizinfo.com, this intersection of technology, sustainability, and governance is likely to remain a critical area of focus as they evaluate partners, investments, and strategic priorities.

Positioning Enterprise Software at the Core of Business Strategy

As 2026 unfolds, the future of enterprise software for business growth is defined by convergence: convergence of technologies such as cloud, AI, and advanced analytics; convergence of strategic priorities around growth, resilience, and sustainability; and convergence of regional markets into a more interconnected yet complex global landscape. For executives, founders, and professionals who rely on upbizinfo to navigate day to day shifts in business, technology, economy, and news, the central message is that enterprise software is no longer a supporting actor in the story of corporate growth; it is a central protagonist that shapes what is possible, how quickly organizations can adapt, and how responsibly they can scale. Decisions about software platforms, architectures, and partnerships are therefore strategic decisions that influence market positioning, operational efficiency, talent attraction, and stakeholder trust across regions from North America and Europe to Asia, Africa, and South America.

Organizations that approach enterprise software as a living, evolving capability-one that is continually refined in response to new technologies, regulatory changes, and market signals-will be better equipped to seize opportunities and navigate risks in the decade ahead. This requires close collaboration between business and technology leaders, a commitment to building digital skills and data literacy across the workforce, and a willingness to experiment with new models while maintaining strong governance and ethical standards. As the global business community continues to grapple with uncertainty and rapid change, upbizinfo.com will remain a dedicated site for analyzing how enterprise software, in all its complexity and potential, is reshaping the foundations of growth, competitiveness, and resilience for organizations worldwide, providing fans with the insights they need to make informed, forward-looking decisions in an increasingly digital economy.